Categories
Buyer Guides, Home Selling TipsPublished September 30, 2026
Should You Sell Your Northern Virginia Home Before Buying the Next One?
Sell first if you need the proceeds for your next purchase or cannot comfortably carry both homes. Buying first can make the move easier if your lender confirms qualification, your cash is available without the sale, and you can absorb a longer overlap. The right order starts with your finances and backup plan—not the next listing you fall in love with.
Chris Colgan Team agents Peter Van Cleave and Jontae Mclean answered this question in September 2026. Both put financial flexibility ahead of a universal “sell first” or “buy first” rule.
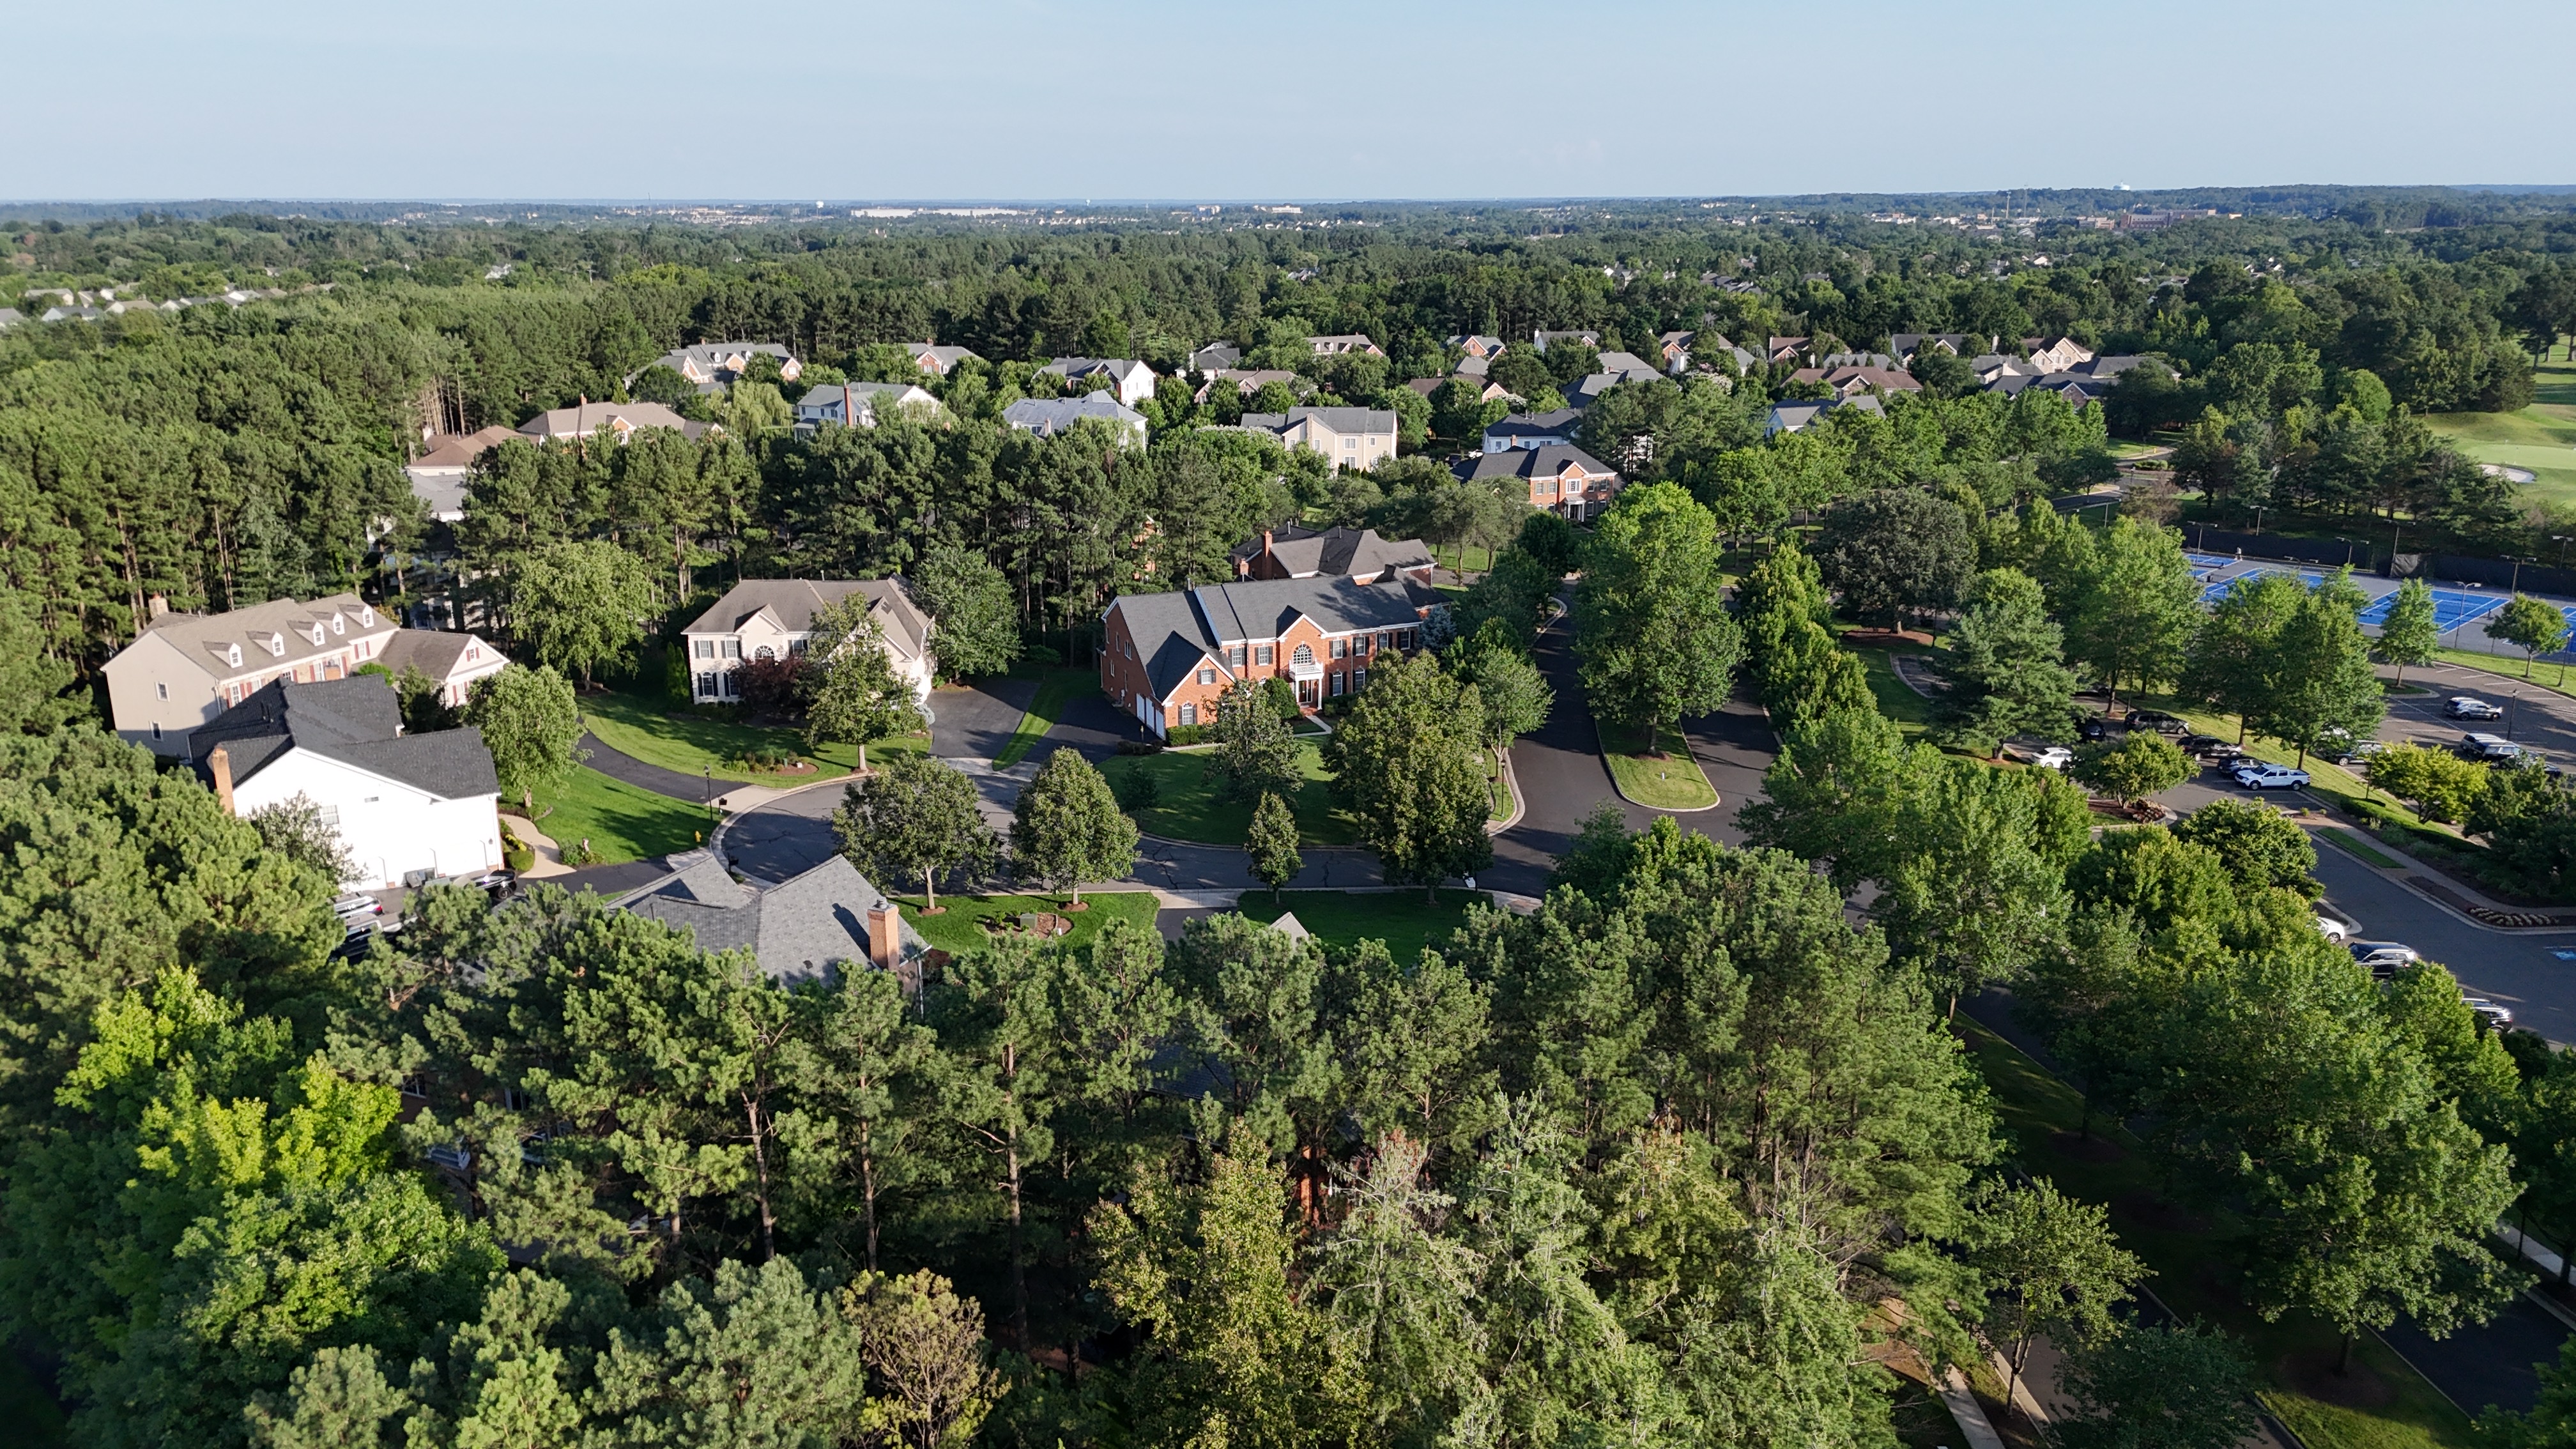
Cover: Dominion Valley homes in the Haymarket area, from our SEO photo library. Neighborhood context only; the pictured homes are not presented as current listings or clients’ properties.
Stay in the know across Northern Virginia.
Get local news, new openings and community updates from Chris Colgan’s Real NoVA newsletter.
Peter’s starting point: do you need the equity?
Peter generally favors selling first when a client needs equity from the current home for the next down payment. If the client can qualify and comfortably carry both homes for a period, he says buying first can reduce the pressure of finding the right home quickly.
Separate three numbers: the estimated sale price, the estimated net proceeds after payoff and selling expenses, and the amount you can actually use toward the next purchase. They are not interchangeable.
Ask for a seller net estimate using a realistic price range, your mortgage payoff and the expenses applicable to your agreement. Then tell the lender which funds are available now and which depend on a completed sale. A pending contract does not put the proceeds in your bank account.
Selling first: more budget clarity, possible housing gap
Selling first can make sense when the next purchase depends on the sale proceeds, overlapping payments would be stressful, or you want the sale completed before taking on another commitment.
The tradeoff is a possible gap between homes. Peter recommends planning for temporary housing, storage, pets and moving costs. Price those items before assuming two separate moves are affordable or easy to arrange.
Consider a homeowner selling in Woodbridge and looking for a different layout in Haymarket. If the sale must fund the purchase, a temporary rental may buy time to evaluate the next home. But the rental, extra move and storage belong in the budget. This is an illustrative scenario, not a reported client transaction.
A negotiated post-settlement occupancy arrangement may be an option, but do not assume a buyer will accept one. Discuss written dates, charges, responsibilities, insurance and lender requirements with the professionals handling the transaction. It is a negotiated arrangement, not automatic permission to stay.
Buying first: easier moving logistics, more financial exposure
Buying first may give you time to move out before preparing and showing the old home. It can also let you search without a temporary-housing deadline. Those advantages matter only if the overlap is manageable.
Jontae recommends checking both qualification and comfort with two mortgage payments. Those are different tests: a lender’s approval does not tell you how much uncertainty you personally want to carry.
For example, an Ashburn owner hoping to buy in Leesburg should compare the costs of both properties, including taxes, insurance, association charges, utilities and maintenance. Test a longer-than-planned overlap and a lower-than-hoped-for sale price. These are planning scenarios, not forecasts for either community.
For loans subject to Fannie Mae’s current pending-sale guidance, the lender generally counts both the current and proposed housing obligations when the existing home will not transfer before the new purchase. The guide provides an exception with an executed sales contract and confirmation that financing contingencies have cleared. Have your lender apply the rules for your specific loan; do not assume every program works the same way.
Jontae’s warning: don’t build the plan around a guaranteed sale date
Jontae’s main concern is a buyer assuming the current home will sell on the preferred timeline. She recommends a realistic understanding of the home’s value, financing options and a backup plan.
A plan that requires an immediate offer, no repair negotiation and perfectly aligned closings leaves little room for normal transaction uncertainty. Write down what you would do if the sale closes later or your next home takes longer to find.
- If the current home takes longer to sell: how long can you carry it, and when will you reassess price or preparation?
- If the next purchase is delayed: where will you stay, and what will another week or month cost?
- If the sale proceeds change: does the down payment still work, and what cash reserve remains?
For the pricing side, read our guide to few showings and deciding whether to reduce the price. For condition-related negotiations, see repairs versus a seller credit.
Prepare the current home before the next one appears
Peter describes working with move-up buyers who prepared their existing home for sale while watching for the next property. His point is preparation: having the current home ready made it possible to respond without a last-minute scramble.
He did not supply a particular neighborhood, price, closing date or sale result, so this is his description of an approach—not a case study claiming a specific outcome.
Before you start serious shopping, build a preparation list, estimate costs, collect the documents your agent requests and discuss a realistic listing strategy. You can prepare without committing to an unsuitable purchase. Our home-staging guide with Peter can help frame that conversation.
Put both transactions on one calendar
Identify the sale and purchase deadlines, lender requirements, expected availability of sale proceeds, possession dates and moving reservations. Ask the settlement professionals how the funds will move between closings. Do not assume two appointments on the same day guarantee a seamless transfer.
A home-sale contingency is something to discuss when preparing an offer; acceptance and protection depend on the negotiated wording and deadlines. Have the actual contract explained before relying on it.
The CFPB’s Closing Disclosure guide explains that lenders must provide that disclosure three business days before scheduled closing. Use that review time to check the loan terms and cash to close with your lender. A disclosure review is one step in coordination, not a guarantee that either closing will happen on schedule.
Five questions about selling before buying
Do I have to sell first if I need the equity?
You need a verified way to fund the purchase. Selling first is often the starting point when the proceeds are essential. Ask your lender about any alternative financing, its costs and what happens if the old home remains unsold.
Can I qualify for a new mortgage while I still own my home?
Possibly. The lender must evaluate the existing obligation, available funds and the new loan’s requirements. Do not assume a listed or pending home is excluded from qualification.
Is buying first always better because I only move once?
No. Avoiding a temporary move can be useful, but compare that convenience with the cash and risk of holding both properties.
Can I stay in my home after selling it?
Only if an appropriate arrangement is agreed. Discuss occupancy terms before counting on that option, including the buyer’s needs and applicable lender and insurance requirements.
What should I do before touring the next home?
Clarify financing, estimated net proceeds, preparation needs and a backup housing plan. Peter and Jontae both emphasize making those decisions before timing becomes urgent.
Let’s build your sell-and-buy plan
Talk with the Chris Colgan Team about selling your current home, including preparation, a realistic price range and estimated proceeds. Then compare your next-home options with our team. Tell us where you own now, where you want to move and which dates are flexible.
Want more Northern Virginia news and local updates?
Join Chris Colgan’s Real NoVA newsletter and get the next edition in your inbox.
Contributing agents
Peter Van Cleave
Colgan Team Agent Partner
571-217-3588 | Peter@ColganTeam.com
Meet Peter Van Cleave
Jontae Mclean
Real Estate Agent, Chris Colgan Team
jontae@colganteam.com
Team office: 571-621-7660
Meet Jontae Mclean
Chris Colgan
Chris Colgan
REALTOR® | Team Leader, Chris Colgan Team
Real Broker, LLC | Powered by PLACE
Call or text: 571-437-7575
Office: 571-621-7660
info@colganteam.com
8427 W Main St, Marshall, VA 20115
ColganTeam.com | ChrisColgan.com
Agent insights supplied September 28, 2026; primary guidance checked September 29, 2026. Examples are illustrative unless explicitly attributed to an agent. Financing and contract terms depend on the transaction.
Chris Colgan
Team Leader | Chris Colgan Team | REAL | PLACE
or another way