Categories
Buyer GuidesPublished October 10, 2026
What a $100K Household Income Buys in Virginia, West Virginia, Maryland and D.C.
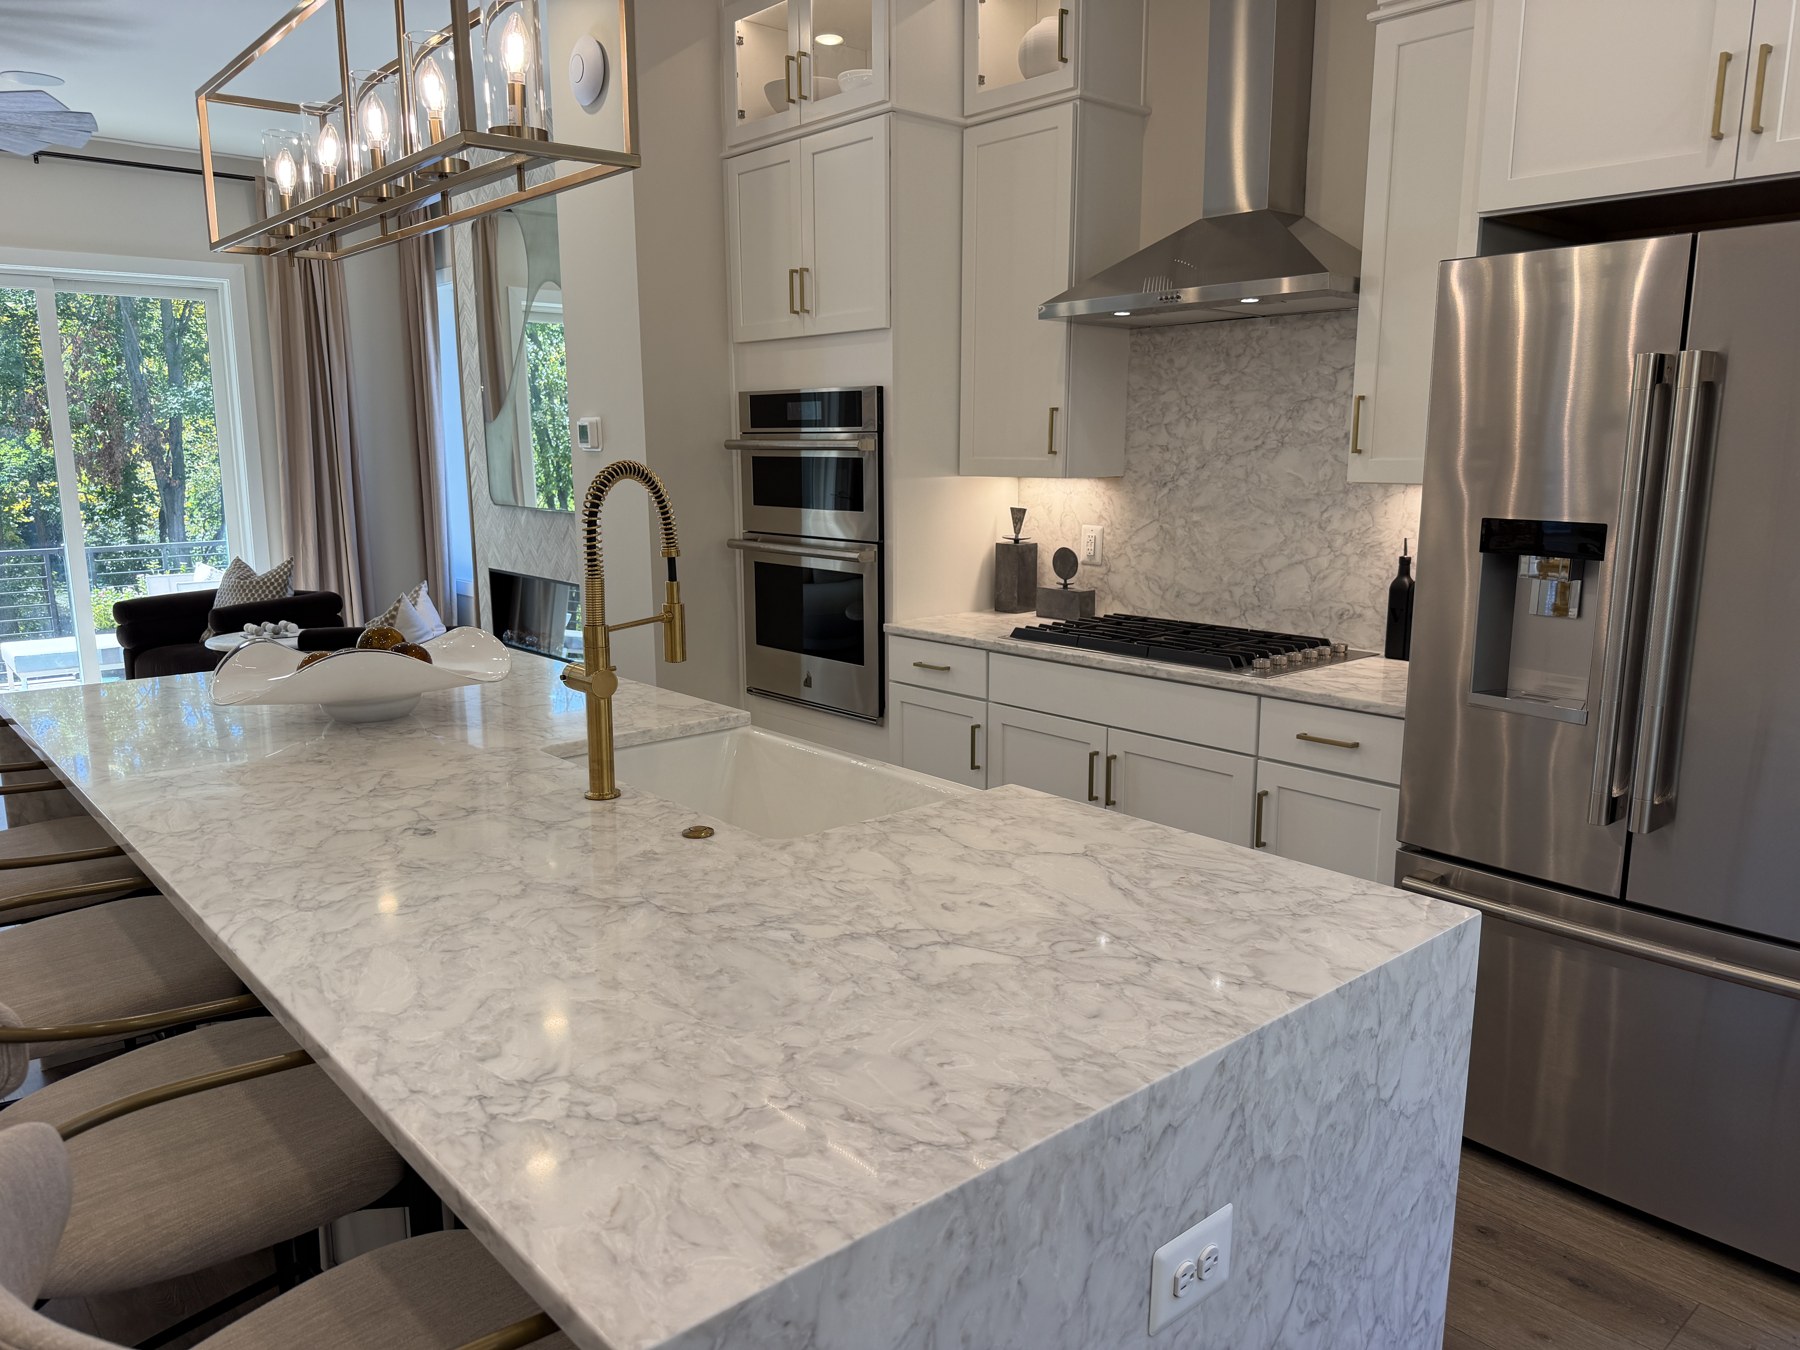
Cover: Chris Colgan’s photo of a model-home kitchen at Sunset Station in Reston. Neighborhood context only; this home is not represented as available at any price in the comparison.
A $100,000 household income does not point to one kind of home across Virginia, West Virginia, Maryland and Washington, D.C. The useful question is how much room your payment leaves for the life you want after you buy. This guide starts with a regional comparison, then works through property type, financing, cash needed and the commute that can change the decision.
The four-area comparison
Zillow’s September 30, 2026 analysis models affordability for a household earning $100,000 annually. Its reported figures are:
| Geography | Modeled price | Median bedrooms | Median space at that price |
|---|---|---|---|
| Maryland statewide | $368,000 | 3 | 1,218 sq. ft. |
| Virginia statewide | $377,000 | 3 | 1,308 sq. ft. |
| West Virginia statewide | $381,000 | 3 | 1,408 sq. ft. |
| Washington, D.C. | $385,000 | 1 | 735 sq. ft. |
Zillow defines affordability here as mortgage, property taxes, insurance and maintenance consuming no more than 30% of monthly household income. These are modeled thresholds and median home characteristics, not loan approvals or promises about available listings.
How to use the four-area comparison
Two homes with similar asking prices can solve completely different problems. One may provide a separate office and guest room. Another may remove a long drive from the workweek. A third may look inexpensive until the association fee and repairs enter the calculation. Decide which problem you need the home to solve before choosing the biggest number in the space column.
Virginia: turn the statewide row into a local search
Virginia includes markets far beyond Northern Virginia. A state-level summary cannot stand in for a search in Arlington, Reston, Manassas or Woodbridge. Start by choosing your work destination and the kind of home you need, then look at current listings that satisfy both. A condo search and a detached-home search should be separate comparisons.
For a Northern Virginia buyer, the first round of touring should answer a practical question: which compromise is easiest to live with? It might be less interior space, an older kitchen, fewer parking spaces or a longer trip to work. Make those tradeoffs explicit. Do not assume that a statewide price estimate guarantees a particular home type in every town—or that it rules out every option before you look.
West Virginia: test the location as carefully as the floor plan
If you are considering a move across the Virginia–West Virginia line, narrow the search to the communities you would actually use. A statewide example elsewhere in West Virginia is not a substitute for checking the Eastern Panhandle. The route to your workplace, the number of office days and the services near the home belong in the same conversation as bedroom count.
Try the round trip on a normal workday. Ask whether the extra room supports something important, such as a dedicated office, or merely looks attractive in a listing. A move can make sense when it fits your actual schedule. It needs another look if it depends on permanently light traffic or never having to return to the office.
Maryland: choose a corridor before choosing a house
Maryland is also too varied for a statewide row to answer a local buying question. Identify the specific county, municipality and commute route for each home. Someone who needs to reach an office in Northern Virginia faces a different search from someone whose regular destinations are in Maryland or D.C.
For every candidate, obtain the property’s tax information, association charges and insurance estimate. Compare those actual costs with the other homes on your list. Do not assume a state line alone determines the cheaper monthly choice. A home that matches your needs near the places you already go deserves a different evaluation from one that adds a new cross-region trip.
Washington, D.C.: work out whether the smaller layout works
For a compact home, room dimensions can be more useful than the bedroom label. Where would a desk go? Is there enough storage? Can you comfortably host the people who visit you? Walk through an ordinary day rather than deciding from a wide-angle photograph.
Then compare the location benefits you would genuinely use. If a home lets you change your driving, parking or transit routine, put that change in your budget using your own numbers. Do not automatically assume you will give up a car. For a condo or co-op, understand the ownership structure, fees, financing requirements and building responsibilities before comparing it with a townhouse or detached home.
Start with the monthly budget
Before choosing a search ceiling, write down the monthly amount you can comfortably commit while preserving savings and other priorities. Then ask a lender to show how that translates into a purchase range using your actual down payment, debt and financing terms.
The Consumer Financial Protection Bureau’s loan-choice guide is a useful starting point for comparing borrowing options. A price target is only one part of the decision; loan structure and upfront costs matter too.
What does $100K mean month to month?
Dividing $100,000 of annual gross household income by 12 gives approximately $8,333 per month before taxes and payroll deductions. Applying a 30% planning benchmark produces $2,500. That is arithmetic, not a recommended payment for every household. Your take-home pay, debts, childcare, savings needs and income stability can make a lower target more comfortable.
Also separate three questions: what a lender may approve, what a comparison model estimates, and what you are comfortable paying. A preapproval does not require you to spend the maximum. Start with a household budget that still works when a repair, insurance renewal or other expense arrives.
A worked payment example: same house, different rate
Illustration only—not current rate quotes or Zillow’s loan assumptions. Suppose a home costs $380,000 and the buyer puts down 20%, or $76,000. That leaves a $304,000 mortgage. On a fully amortizing 30-year fixed loan, the approximate principal-and-interest payment would be:
| Illustrative annual interest rate | Monthly principal and interest |
|---|---|
| 6.0% | $1,823 |
| 6.5% | $1,921 |
| 7.0% | $2,023 |
These calculations exclude property taxes, insurance, association dues, maintenance, utilities and closing costs. The one-percentage-point difference in this example changes principal and interest by about $200 a month. That is why a purchase-price target needs to be paired with a real lender quote rather than a rate you saw in an old article.
Build the rest of the payment before deciding
Continue the 6.5% example with purely hypothetical monthly costs: $350 for property taxes, $125 for homeowners insurance and $200 set aside for maintenance. Added to $1,921 in principal and interest, that produces about $2,596 before any association fee or utilities. A hypothetical $350 monthly association charge would raise that total to about $2,946. These invented cost inputs demonstrate the worksheet; they are not estimates for any town or property.
The CFPB explains why principal and interest differ from the total payment. Ask which taxes and insurance are escrowed and which expenses you pay separately. When an association covers an item already in your worksheet, adjust the budget to avoid counting it twice.
Down payment and cash to close are different numbers
For that same hypothetical $380,000 purchase, 5% down is $19,000, 10% is $38,000 and 20% is $76,000. The corresponding starting loan balances would be $361,000, $342,000 and $304,000, before any financed fees. Those are down-payment examples, not a statement that every loan program offers every option.
A smaller down payment preserves some cash but changes the amount financed and may change insurance, fees or the available rate. The CFPB’s mortgage-insurance guide explains that requirements vary by loan type; many borrowers putting less than 20% down pay mortgage insurance. Ask the lender to show the complete payment for each option you qualify for.
Keep closing costs, prepaid items, moving expenses and an after-closing reserve on separate lines. The Loan Estimate explainer can help you read projected payments and estimated cash to close. Compare written estimates using consistent assumptions, and ask what each quote includes.
Virginia buyers can also review Virginia Housing’s loans and grants with a participating lender. Assistance has program rules and eligibility requirements; earning $100,000 alone does not establish eligibility. Do not build an offer around an assumed grant until the lender confirms the relevant requirements and availability.
The Northern Virginia question needs a local answer
A statewide summary is not a neighborhood inventory report. The Virginia row does not establish that the same amount buys only a condo throughout Northern Virginia. A useful local comparison needs a search area, property type, current availability and the monthly costs of individual homes.
Choose two or three communities that work for your routine. Compare the actual homes that meet your needs, then test the drive to work, family and the places you use weekly. Space that looks attractive online can become less useful if the location makes everyday life harder.
Build an apples-to-apples shortlist
- Monthly costs: Ask for an estimate for each property, including any association dues and costs outside the mortgage payment.
- Cash needed: Separate down payment, closing costs, moving expenses and reserves.
- Condition: Compare expected maintenance and repairs rather than judging value only by square footage.
- Daily life: Test the commute and think about how often you will use the extra room.
Send the Chris Colgan Team your monthly comfort range, target areas and must-haves. We can help build a Northern Virginia home shortlist to review alongside your lender’s figures.
Condo, townhouse or detached home: compare responsibilities
A condo fee is not just a number to dislike. Read what it pays for, then examine the building’s budget, reserves, maintenance plans and any disclosed assessments. Ask about parking, storage, rental rules and the condition of shared systems. A lower listing price with a high recurring fee may not produce the monthly savings you expected.
A townhouse can have a different mix of exterior responsibilities and association charges. Confirm the ownership structure and the actual documents; the appearance of the building does not tell you who maintains the roof or other exterior elements. With a detached home, make room in the budget for the systems and exterior work that fall to you.
For all three, look beyond cosmetic finishes. Ask your inspector and appropriate specialists about issues within their scope, and obtain repair estimates where needed. A freshly painted home and a well-maintained home are not necessarily the same thing.
Price the commute in hours as well as dollars
Here is another hypothetical comparison. If one location adds 30 minutes each way on three office days a week, that is three additional hours per week. Over four weeks, it becomes 12 hours. That calculation does not say the move is wrong; it makes the trade visible before you commit.
Add your expected fuel, parking, transit and toll costs. Consider a backup route and what would happen if your work schedule changed. For a household with two commuters, calculate both trips. A location that solves one person’s commute but complicates the other deserves a joint decision rather than a quick price-per-square-foot comparison.
A practical first-week home-search plan
- Set the monthly comfort range. Include savings and other priorities before working backward to a price.
- Talk with lenders. Review financing choices and the documentation they need. Request comparable written estimates when you are ready to evaluate offers.
- Pick two or three workable search areas. Use actual destinations and travel routines to narrow the geography.
- Tour a small, representative set. Compare realistic homes across the property types you are considering, using the same checklist each time.
- Price the individual home. Add its taxes, dues, insurance, condition and travel costs before deciding what to offer.
Keep a simple scorecard for each property: full monthly cost, cash needed, rooms you will use, expected work, parking and the commute. This turns a broad four-area comparison into a decision about homes you can actually evaluate.
Watch: comparing Northern Virginia locations
My Reston-versus-Arlington video explores space, surroundings and everyday convenience. It is local context, not a calculation of the Zillow affordability figures.
Watch Chris’s Reston-versus-Arlington comparison.
Five buyer questions
Does household income mean one person’s salary?
It refers to the household total used in the comparison. An individual borrower’s qualifying income still needs lender review.
Can I use the table as a preapproval?
No. A lender must evaluate your circumstances and the proposed financing.
Should I pick the biggest home?
Start with how you will use the space. Layout, condition, location and carrying costs can matter more than the largest floor-area number.
How should I compare a condo with a detached home?
Compare the full monthly costs and responsibilities, including association dues, maintenance arrangements and any restrictions relevant to your plans.
What should I bring to a first buyer conversation?
Your comfortable monthly budget, available cash, timeline, commute destinations and non-negotiable needs. Share detailed financial information securely with your lender.
Source checked October 10, 2026. The source does not establish a down payment, interest rate or loan term in the text reviewed; do not treat the figures as a personalized borrowing limit.
Turn your budget into a Northern Virginia shortlist
Send the Chris Colgan Team your target monthly payment, preferred areas, work destinations and timeline. We can help compare current homes and neighborhood tradeoffs while your lender works through the financing. If you need to sell first, include that timing in the plan.
Call or text 571-437-7575 · Check your current home’s value
About Chris Colgan
Chris is a lifelong Northern Virginian with more than two decades of real estate experience. He leads the Chris Colgan Team at Real Broker, LLC, powered by PLACE, helping buyers and sellers compare neighborhoods and plan their next move.
Chris Colgan
Team Leader | Chris Colgan Team
Real Broker, LLC | Powered by PLACE
Call/text: 571-437-7575
Office: 571-621-7660
info@colganteam.com
8427 W Main St, Marshall, VA 20115
Chris Colgan
Team Leader | Chris Colgan Team | REAL | PLACE
or another way