Categories
Buyer Guides, Housing Market UpdatesPublished September 18, 2026
Why Is Buying Your First Home in Northern Virginia Still So Hard?
By Chris Colgan | Chris Colgan Team | Real Broker, LLC
September 18, 2026
More homes for sale does not automatically mean more homes you can afford. A first-time buyer needs the right combination of purchase price, monthly payment, cash to close, location, and condition. A larger selection helps only if enough of those homes fit that combination.
A new Bright MLS report highlights the pressure on first-time buyers across the Mid-Atlantic. For Northern Virginia buyers, the useful question is what to change in your search—and what not to sacrifice just to get an offer accepted.
What Bright MLS found
In its August 27, 2026 analysis of subscriber surveys, Bright MLS reported these results for buyers who closed in July:
| Measure | First-time buyers | Repeat buyers |
|---|---|---|
| Searched longer than six months | 20.4% | 13.4%* |
| Made offers on multiple properties | 61.6% | Not quoted here |
| Paid above original asking price | 41.4% | 37.5% |
First-time buyers accounted for 36.7% of the surveyed July closings. These are Mid-Atlantic survey findings, not Northern Virginia-only figures, and they describe successful buyers—not everyone who tried to buy. They do not predict your odds of winning a particular home.
*Bright describes the repeat-buyer search category as six months or longer. The article does not provide a county-level breakdown of these buyer experiences.
Why a slower market can still feel competitive
Think about your actual search: perhaps you need a home within a fixed payment, enough bedrooms, a manageable commute, and no major repairs immediately after closing. The number of listings across the county is not the number that passes those tests.
More expensive homes, properties needing substantial work, or homes outside your travel range can increase inventory without giving you another practical option. Meanwhile, a well-priced home that meets your needs may also meet many other buyers’ needs.
That is why two things can be true at once: one seller cuts the price after several weeks, while another receives competing offers. We need to investigate the individual listing instead of assuming the whole region has become equally negotiable.
Have a price range but no clear plan? Book a first-home planning conversation. Bring your target payment, preferred locations, and timing so we can identify the questions to resolve with your lender.
Start with the payment—not the maximum preapproval
A lender’s approval and the payment you are comfortable living with are different decisions. Your household still needs room for transportation, utilities, repairs, savings, and the rest of your life.
Here is a hypothetical comparison using 5% down, a 30-year fixed loan, and a 6.75% interest rate. This is an illustration, not a current rate quote or loan offer.
| Purchase price | 5% down payment | Monthly principal and interest |
|---|---|---|
| $450,000 | $22,500 | $2,773 |
| $550,000 | $27,500 | $3,389 |
| $650,000 | $32,500 | $4,005 |
These payments exclude property taxes, homeowners insurance, mortgage insurance, and HOA or condo fees. The down payments exclude closing costs and reserves. Actual eligibility, pricing, and required cash depend on the loan and borrower.
Ask for a property-specific estimate before treating a home as affordable. The CFPB’s Loan Estimate guide explains projected payments and estimated cash to close. Also ask which expenses are outside the quoted payment.
For example, a condo with a lower purchase price deserves a full comparison that includes its monthly association fee. A house farther away deserves a comparison that includes your actual travel costs and time. Neither choice is automatically better.
Change the search without ignoring the tradeoffs
The best alternative is one you can live with after the excitement of closing wears off.
| Option to compare | What it may change | What to investigate |
|---|---|---|
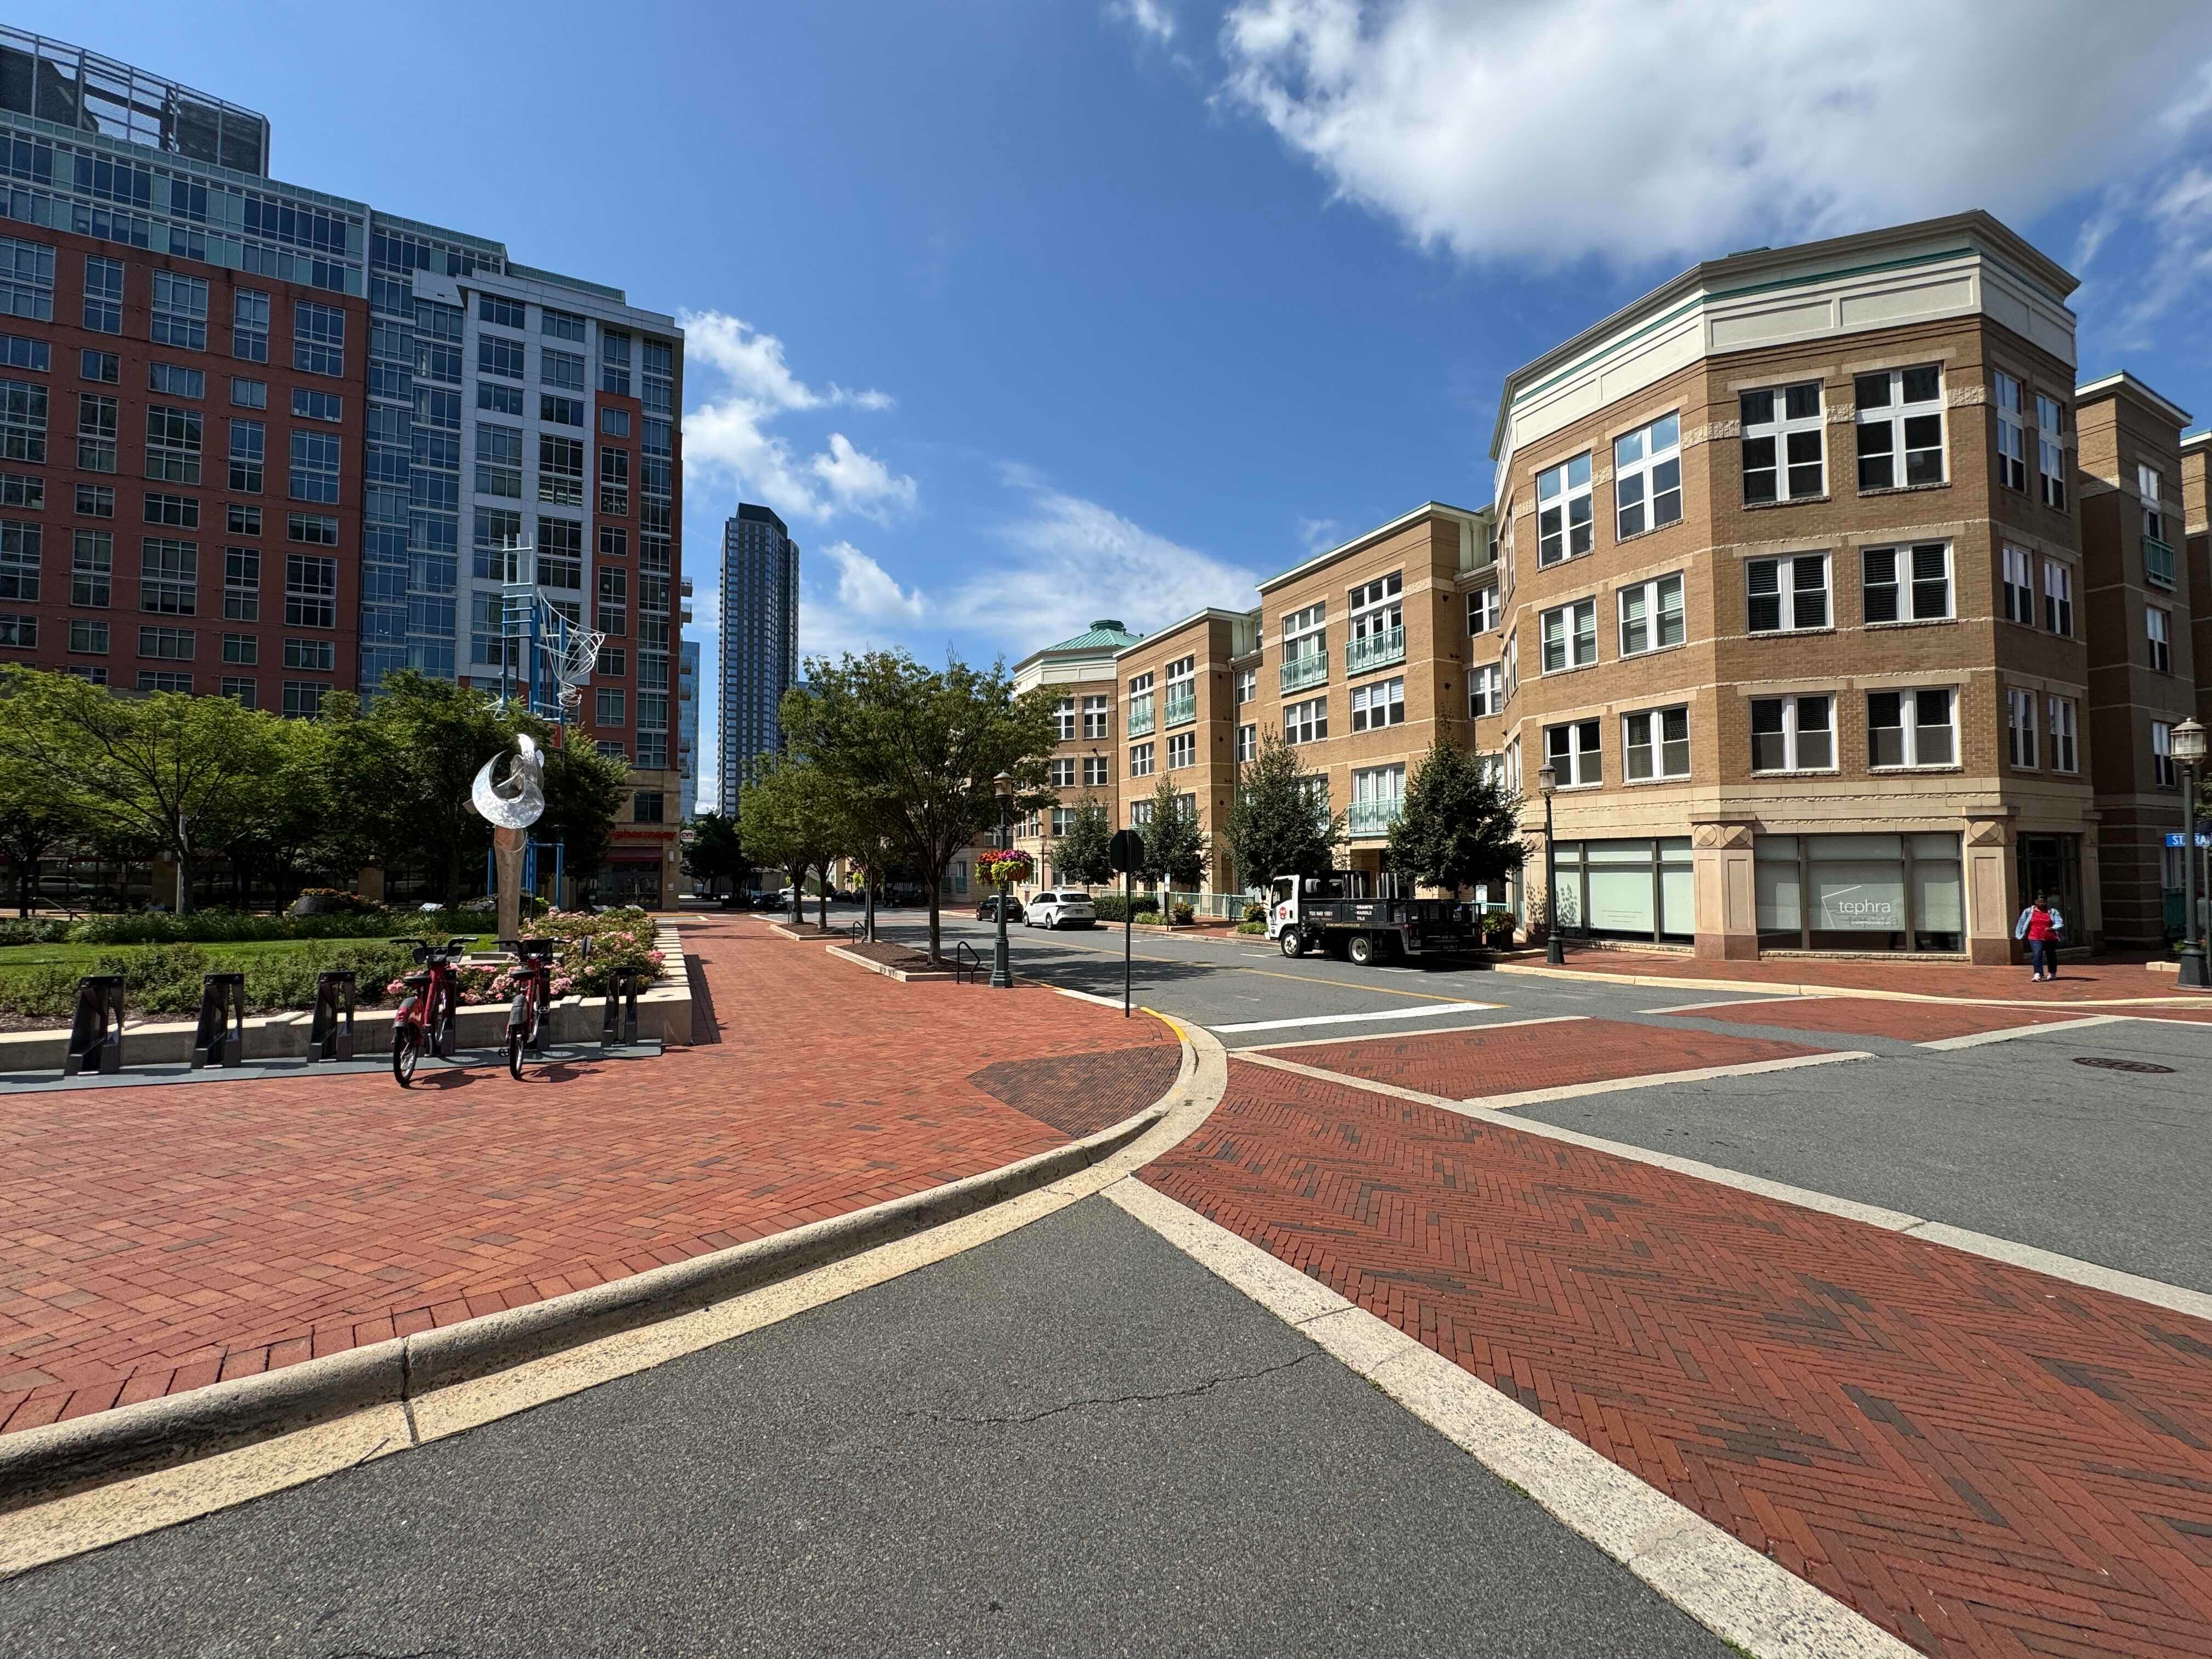
| Condo instead of townhome or detached home | Purchase price, space, maintenance responsibilities | Association fees, documents, reserves, assessments, and financing eligibility |
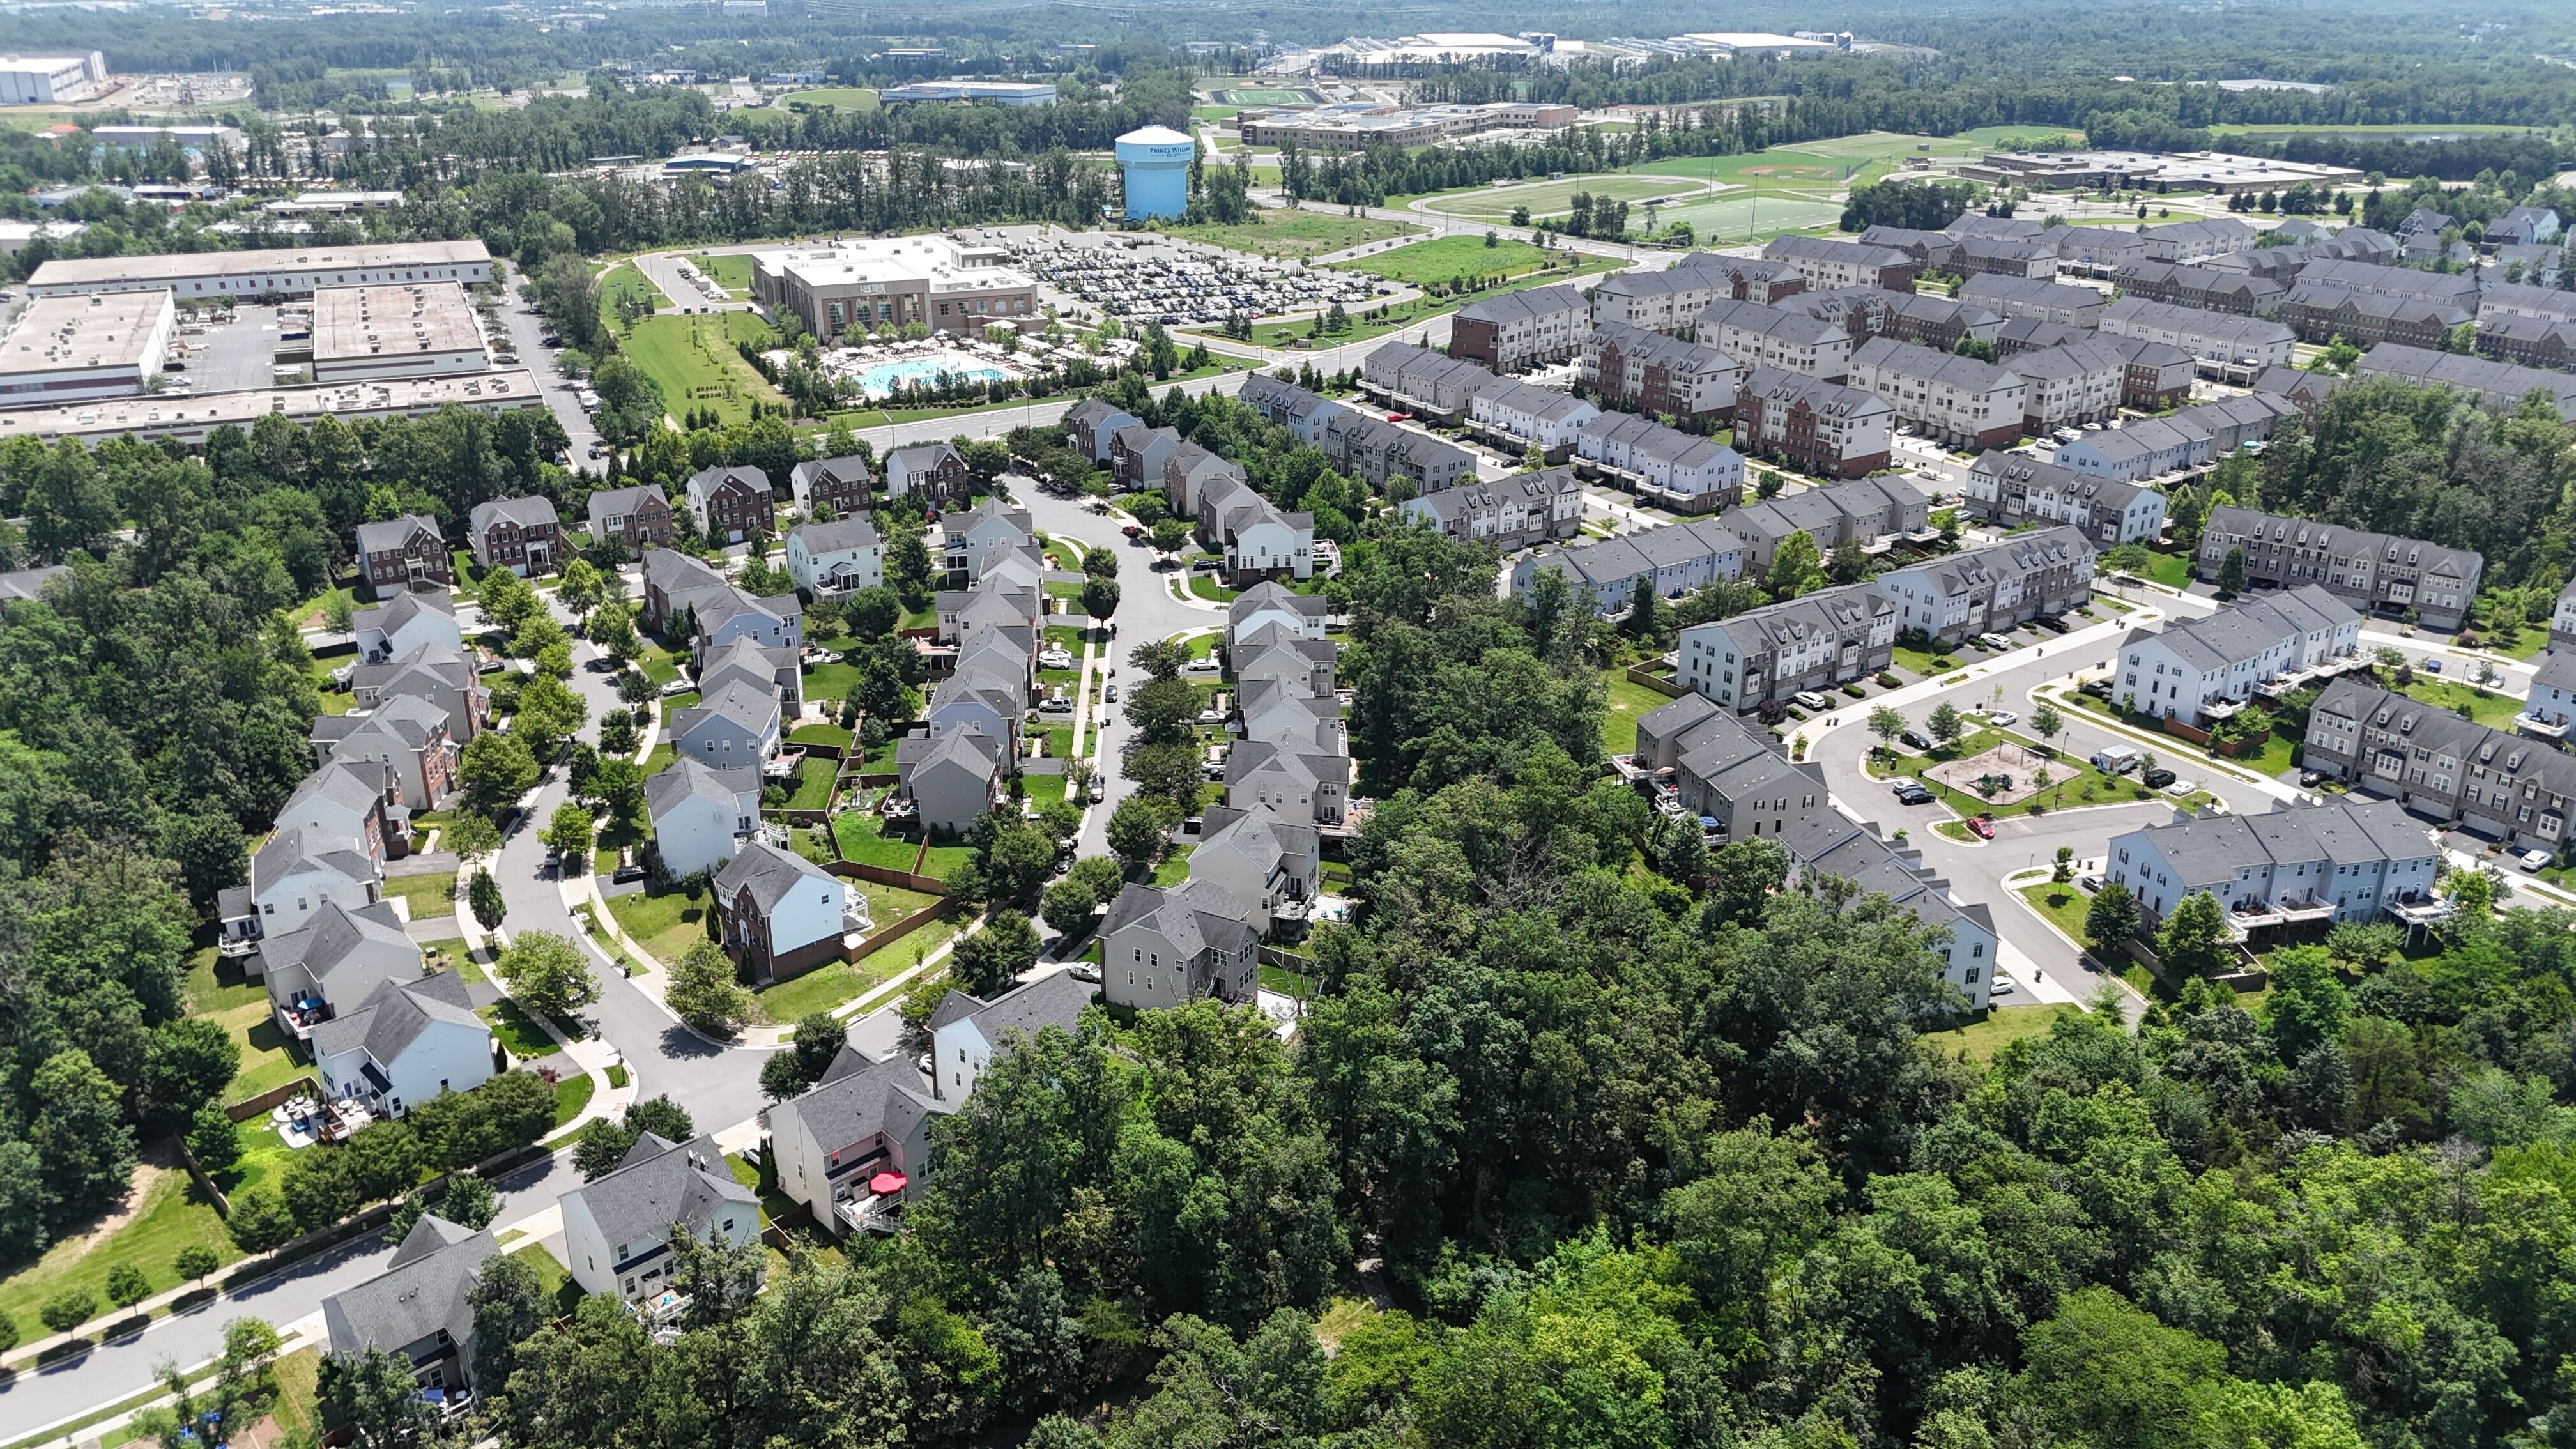
| Woodbridge or another Prince William location instead of a Fairfax search | Available homes within your budget | The actual commute to your workplace, transportation costs, and property condition |
| Stafford instead of a closer-in location | The mix of homes within your search | Travel time on the days you commute, your schedule, and the full payment |
| A home needing cosmetic updates | Competition and potential negotiation | Whether the work is truly cosmetic, contractor estimates, and cash needed after closing |
These are comparisons to run, not promises that a particular area or property type is cheaper. Test a commute at the relevant time and compare actual listings. Do not use a county median as a quote for a particular neighborhood.
If a home needs a roof, major systems, or structural work, a lower asking price may not solve the budget problem. Separate repairs you can comfortably fund from projects you are merely hoping will be inexpensive.
My offer strategy starts with a phone call
Before writing an offer, I call the listing agent and ask whether there are competing offers. That is part of the approach I explained in my Northern Virginia guide to offering below asking price.
No competing offers can open a different conversation, but it does not prove that the seller will accept a large discount. We still look at comparable sales, condition, pricing history, and your alternatives.
If you need to preserve cash, a request for eligible closing-cost assistance may deserve a comparison with a lower purchase price. On a hypothetical $500,000 purchase, a 2% seller credit would be $10,000. Your lender must confirm permitted credits and eligible costs; the seller considers the total effect on their proceeds.
Discuss contract protections before deciding how to compete. Losing a home is disappointing. Winning one with costs or risks you cannot manage can be worse.
Check assistance before you rule yourself out
Virginia Housing offers grants and loan options, including down-payment assistance for qualified buyers. Its grant and second-mortgage options are different products; do not assume all assistance is money that never needs repayment.
Ask a participating lender to check your eligibility, the property, current income and sales-price limits, education requirements, and the combined payment. The Down Payment Assistance Grant page is a useful starting point. Assistance can address one part of the purchase without making the overall monthly cost comfortable.
Also compare the full loan package, including rate, fees, and repayment terms. Do not choose financing solely because the advertised upfront contribution is larger.
When buying now fits—and when waiting makes sense
Buying may fit when you have a sustainable full payment, funds for closing and unexpected repairs, a location that works, and a reasonable expectation of staying long enough to justify the costs of moving.
Waiting may fit when the payment works only if rates fall, closing would use nearly all your accessible savings, your employment or location is unsettled, or every available home requires a compromise you already resent.
Waiting is not a guarantee of lower prices. Buying is not a guarantee of quick appreciation. Compare the costs and flexibility of both choices using your circumstances, rather than a prediction you need to come true.
Northern Virginia market context: more inventory, different price points
The team’s August 2026 Bright MLS/SmartCharts reference shows how widely countywide prices differ. These figures cover all property types and are separate from Bright’s July buyer survey.
| Jurisdiction | August 2026 median sold price | Active listings change vs. August 2025 |
|---|---|---|
| Fairfax County | $752,250 | +20.3% |
| Loudoun County | $771,250 | +17.6% |
| Prince William County | $599,900 | +24.3% |
| Stafford County | $545,000 | +19.5% |
| Fauquier County | $675,000 | +13.8% |
| Arlington County | $860,729 | +12.2% |
| Alexandria City | $752,500 | +22.6% |
Source: Bright MLS via SmartCharts/MarketStats by ShowingTime, August 2026; calculated September 4, 2026. Historical figures, not live inventory or starter-home prices. Fairfax County excludes Fairfax City; Prince William County excludes Manassas and Manassas Park; Alexandria City excludes Fairfax County homes with Alexandria mailing addresses. Median-price differences do not compare identical homes.
Five questions first-time buyers ask
Does more inventory mean I should offer below asking?
Not automatically. Compare the home with relevant recent sales, check its condition and pricing history, and find out whether the seller has other offers. A county inventory increase cannot choose your offer price.
Should I expect my search to take six months?
Build flexibility into your plan, but do not treat six months as a required timeline. Your budget, financing, needs, available homes, and competition affect how long a workable purchase takes.
Is a condo always the cheapest way to buy?
No. Compare the full monthly cost, cash needed, association obligations, and likely maintenance responsibilities. A lower purchase price can come with expenses that change the comparison.
Can a seller credit help with my down payment?
Eligible credits generally address permitted closing expenses rather than directly funding the down payment. They may preserve some of your own cash. Ask your lender what your specific loan allows before writing the request into an offer.
Should I wait for mortgage rates to fall?
Do not base an otherwise uncomfortable purchase on a future refinance. Compare buying at terms available to you now with continuing to rent and save. Future rates, prices, and refinance eligibility are uncertain.
Make the first purchase work for your life
Send me two or three listings you are considering and tell me what worries you most: monthly payment, cash to close, competition, condition, or the commute. We can focus the search around those constraints and coordinate the financing questions with your lender.
Book a 30-minute first-home planning conversation. Still deciding where to live? Get the Northern Virginia relocation guide.
Chris Colgan
REALTOR® | Team Leader, Chris Colgan Team
Real Broker, LLC | Powered by PLACE
Call or text: 571-437-7575 | Office: 571-621-7660
info@colganteam.com
8427 W Main St, Marshall, VA 20115
ColganTeam.com | ChrisColgan.com
Chris Colgan
Team Leader | Chris Colgan Team | REAL | PLACE
or another way