Categories
Home Selling Tips, Investment PropertiesPublished October 1, 2026
Should You Sell Your Northern Virginia Townhouse or Keep It as a Rental?
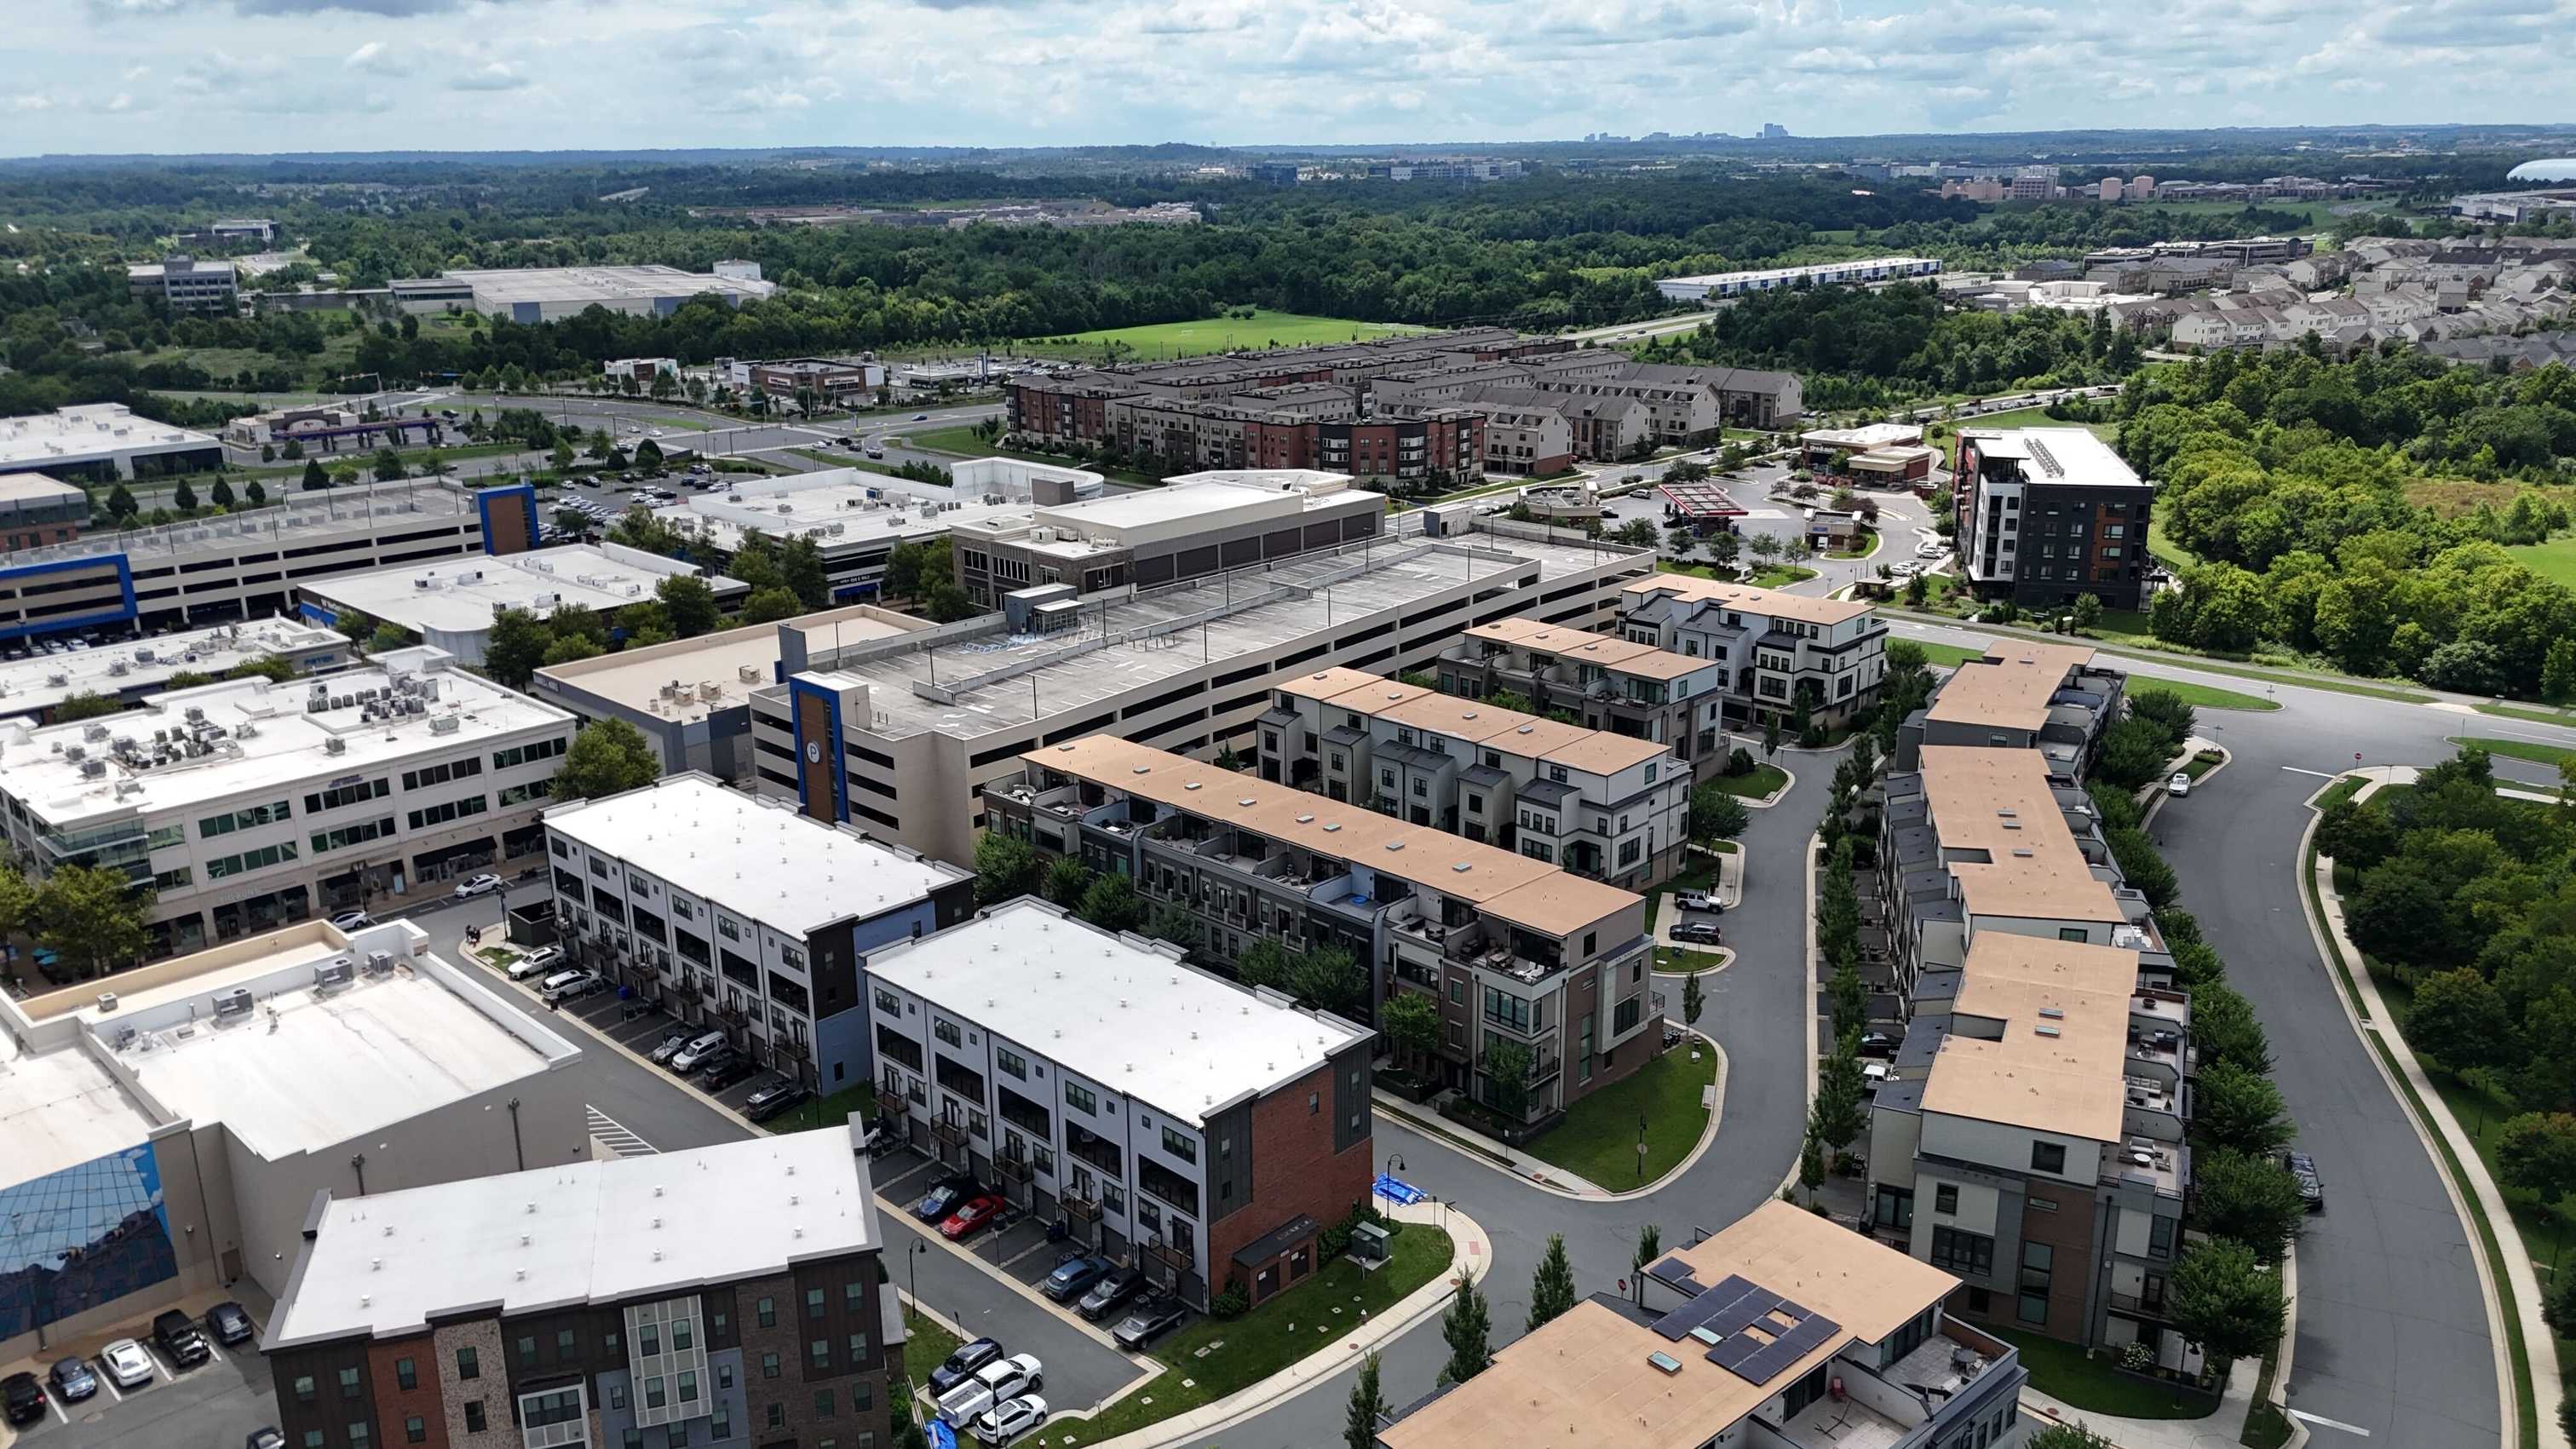
Cover: townhomes at One Loudoun in Ashburn, Virginia. Community context from the team’s local photo library; not a rental listing or the property in the hypothetical budget.
The short answer: Keeping your townhouse as a rental can make sense if the rent supports the full cost of ownership, you have money for repairs and vacancies, and you can buy your next home without relying on the sale proceeds. Selling may be the better choice if you need the equity, the rental would strain your budget, or you do not want the responsibilities of a landlord.
One of the first things I tell Northern Virginia homeowners is that owning a rental and making money every month are two different things. In my experience helping people weigh this choice, monthly cash flow can be difficult to achieve here. A home can command substantial rent and still leave its owner paying out of pocket.
My starting point is simple: the rent needs to cover your payment at a minimum. But that is only the first test. Before keeping a townhouse in Fairfax, Ashburn, Manassas, Bristow, or elsewhere in Northern Virginia, we need to look at the expenses around that payment—and what keeping the property does to your next move.
Stay in the know across Northern Virginia
Get local news, new openings and community information from Chris Colgan’s Real NoVA newsletter.
The decision: When does selling make more sense than renting?
| Question | Selling may fit better when… | Keeping it may fit better when… |
|---|---|---|
| Do you need the equity? | The sale proceeds are needed for your next down payment, closing costs, or reserves. | You can fund the next purchase and keep adequate cash available without selling. |
| Does the rental budget work? | Realistic rent leaves a shortfall after expenses and reserves. | The budget supports the full costs, with room for surprises. |
| What condition is the home in? | Upcoming repairs would leave you stretched. | You have evaluated the roof, HVAC, and other systems and funded a repair plan. |
| Do you want to manage tenants? | You do not want the work and paid management makes the numbers unattractive. | You are willing to manage it or can afford a clearly defined management service. |
| What is your holding plan? | You want a simpler move or are uncomfortable tying up the money. | You want to own the property long term and can absorb setbacks. |
No single answer settles the decision. A low mortgage payment helps, but it does not eliminate maintenance. A large mortgage balance matters, but it also does not tell us the likely rent, selling costs, or cash you would receive at closing.
Rent covering the mortgage is not the same as breaking even
Start with your actual mortgage statement. Does the payment include property taxes and insurance? Then add HOA or condo dues, any mortgage insurance not already counted, and other expenses you would still pay as the owner. Avoid counting the same expense twice.
Next, budget for the months when the home is vacant, routine repairs, future replacements, leasing costs, and management if you plan to use it. Your insurer should also review the change from owner occupancy to rental use.
A hypothetical townhouse rental budget
The following example shows how an apparent monthly surplus can disappear. These are illustration numbers, not a Northern Virginia rent estimate, contractor quote, or property-management fee survey.
| Monthly item | Illustrative amount |
|---|---|
| Scheduled rent | $3,200 |
| Mortgage payment, including taxes and insurance | −$2,450 |
| HOA dues | −$150 |
| Vacancy allowance: 5% of scheduled rent | −$160 |
| Routine maintenance reserve | −$250 |
| Major replacement reserve | −$175 |
| Management: hypothetical 8% of scheduled rent | −$256 |
| Allowance for leasing and turnover costs | −$50 |
| Monthly cash remaining after expenses and reserves | −$291 |
Looking only at $3,200 in rent minus a $2,450 payment suggests $750 left over. This fuller budget produces a $291 monthly shortfall. Self-managing would remove the hypothetical $256 management charge, but the example would still be $35 short—and you would be doing the work.
Reserves are money set aside for future bills, not necessarily spent every month. This is a planning calculation before income taxes; it is not a tax-profit calculation. Replace every assumption with figures for your property.
Want to compare the two paths for your townhouse?
We can help you review likely sale proceeds, comparable rentals, and how each option affects your next purchase.
Compare Selling vs. Renting My HomeHow much should you keep available for repairs?
I tell homeowners considering a rental to think about having $5,000–$10,000 set aside for unexpected issues. That is a starting conversation, not a promise that it will cover everything. An older roof, aging HVAC, a vacancy, or several problems at once may require more.
“They're going to be calling you when the heat's not working or the AC stops.” — Chris Colgan
Before deciding, review the age and condition of the roof, heating and cooling equipment, water heater, appliances, and plumbing. Get estimates for known problems instead of hoping a reserve will be enough.
For a townhouse, confirm what the association actually maintains. Do not assume an HOA pays for the roof or exterior; responsibilities depend on the property's ownership structure and governing documents. Keep rental reserves separate from the money needed to move and support your own household.
What if you need the equity to buy your next home?
This often changes the conversation. If the sale proceeds are what make the next home affordable, holding onto the townhouse may create a problem that rental income does not solve.
Compare the estimated sale price with the mortgage payoff and anticipated selling costs to estimate your proceeds. For an initial pricing conversation, you can request a home valuation. The next step is a property-specific estimate of what you could actually receive.
Equity is not the same as cash in your account. Accessing it without a sale generally requires financing or another arrangement, with its own qualification requirements, costs, and repayment obligations.
Also ask your lender how keeping the home would affect approval for the next purchase. Do not assume all expected rent will count as qualifying income. Fannie Mae has specific departing-residence rental-income rules; your loan program, documentation, and lender review determine what applies.
Do you actually want to be a landlord?
I ask this directly because a spreadsheet cannot answer it. Are you comfortable dealing with repair calls, scheduling vendors, reviewing applications, maintaining records, and managing a vacancy?
A property-management company can handle agreed tasks, but you need to know exactly what you are buying. Ask about:
- Monthly management fees and separate leasing or renewal charges.
- Who answers emergency calls and authorizes repairs.
- Repair spending limits, vendor selection, and any maintenance markups.
- Inspections, owner reports, and handling of late rent.
- Services that cost extra and how the agreement can be ended.
Use an actual proposal in your budget. Hiring a manager does not make the property's expenses disappear. Review Virginia's landlord and tenant resources before offering the home for rent, and get help with a compliant lease and rental process.
What should you check locally before making the decision?
Use rental comparisons for the same type of townhouse in the same community or a genuinely comparable nearby area. Match bedroom count, bathrooms, garage spaces, condition, size, and lease terms. A garage townhouse in Ashburn is not an interchangeable rental comparison for a different property in Manassas or Bristow.
Look at competing listings and completed leases when available. An advertised rent is an asking price, not proof that a tenant agreed to pay it. Check association rental restrictions and any applicable local requirements before committing.
If selling looks stronger, compare that option with your next purchase. Read our guide to the cost of moving up in Prince William County for a related planning discussion.
Can keeping the townhouse help build wealth?
I believe owning real estate can be part of building long-term wealth. Keeping a property may give you future rental income, loan paydown, and exposure to changes in its value.
But appreciation is not guaranteed, and equity growth does not pay an HVAC bill today. Separate the long-term investment case from the cash you need to operate the property now. Consider what else the sale proceeds could do for you, including reducing the amount you need to borrow on the next home.
There is also a tax decision. Converting a former primary residence to a rental can affect the tax treatment of a later sale, and depreciation can create taxable gain that is not covered by the home-sale exclusion. Ask your CPA to compare selling now with renting and selling later. IRS Publication 523 explains the ownership, use, and other requirements; do not assume a future sale will be tax-free.
Considering the selling path? Watch Chris’s advice
In this 2022 video, Chris shares six questions to ask when choosing an agent to sell your home. It covers the selling side of the decision, not rental underwriting. Brokerage references in the video are historical; current contact information appears below.
Watch Chris’s home-selling advice on YouTube.
Frequently asked questions
Should I keep my townhouse just because I have a low interest rate?
A low rate may improve the rental budget, but it is only one input. Compare the full costs, required reserves, accessible cash for your next purchase, and your willingness to manage the property.
Is $5,000 enough in rental reserves?
It may be inadequate for your home. My $5,000–$10,000 starting point needs to be adjusted for known repair needs, system ages, vacancy exposure, and your ability to cover a larger bill.
Can I count the rent toward qualifying for my next mortgage?
Possibly, subject to the lender's documentation and loan-program rules. Have the lender evaluate the scenario before relying on anticipated rent to qualify.
What if the rental only breaks even?
First establish what “breaks even” includes. Covering the mortgage alone leaves out meaningful costs. A property that covers full expenses and reserves may still fit a long-term plan, but you should understand the risks and what your equity could accomplish elsewhere.
Will you tell me if selling is the better option?
Yes. The goal is to make the next move work for you. If keeping the townhouse leaves you short of cash, uncomfortable with the payments, or responsible for work you do not want, we should discuss selling.
Keep up with Northern Virginia
Join Chris Colgan’s Real NoVA newsletter for local news and community updates in your inbox.
Get a selling-versus-renting plan for your home
Bring your current mortgage payment, HOA or condo dues, approximate loan balance, known repair needs, and next-home goals. We can help compare the property with local sales and rentals, then coordinate with your lender, CPA, or a property manager where their input is needed.
Compare Selling vs. Renting My Home
Chris Colgan Team
Real Broker, LLC | Powered by PLACE
Call/text: 571-437-7575
Office: 571-621-7660
info@colganteam.com
Connect with Chris and the team
Educational information; individual financing, tax and legal questions should be reviewed with the appropriate professional. Sources checked October 1, 2026.
Chris Colgan
Team Leader | Chris Colgan Team | REAL | PLACE
or another way