Categories
For Sellers, Northern Virginia Real EstatePublished October 18, 2026
Is the Highest Offer the Best Offer on Your Northern Virginia Home?
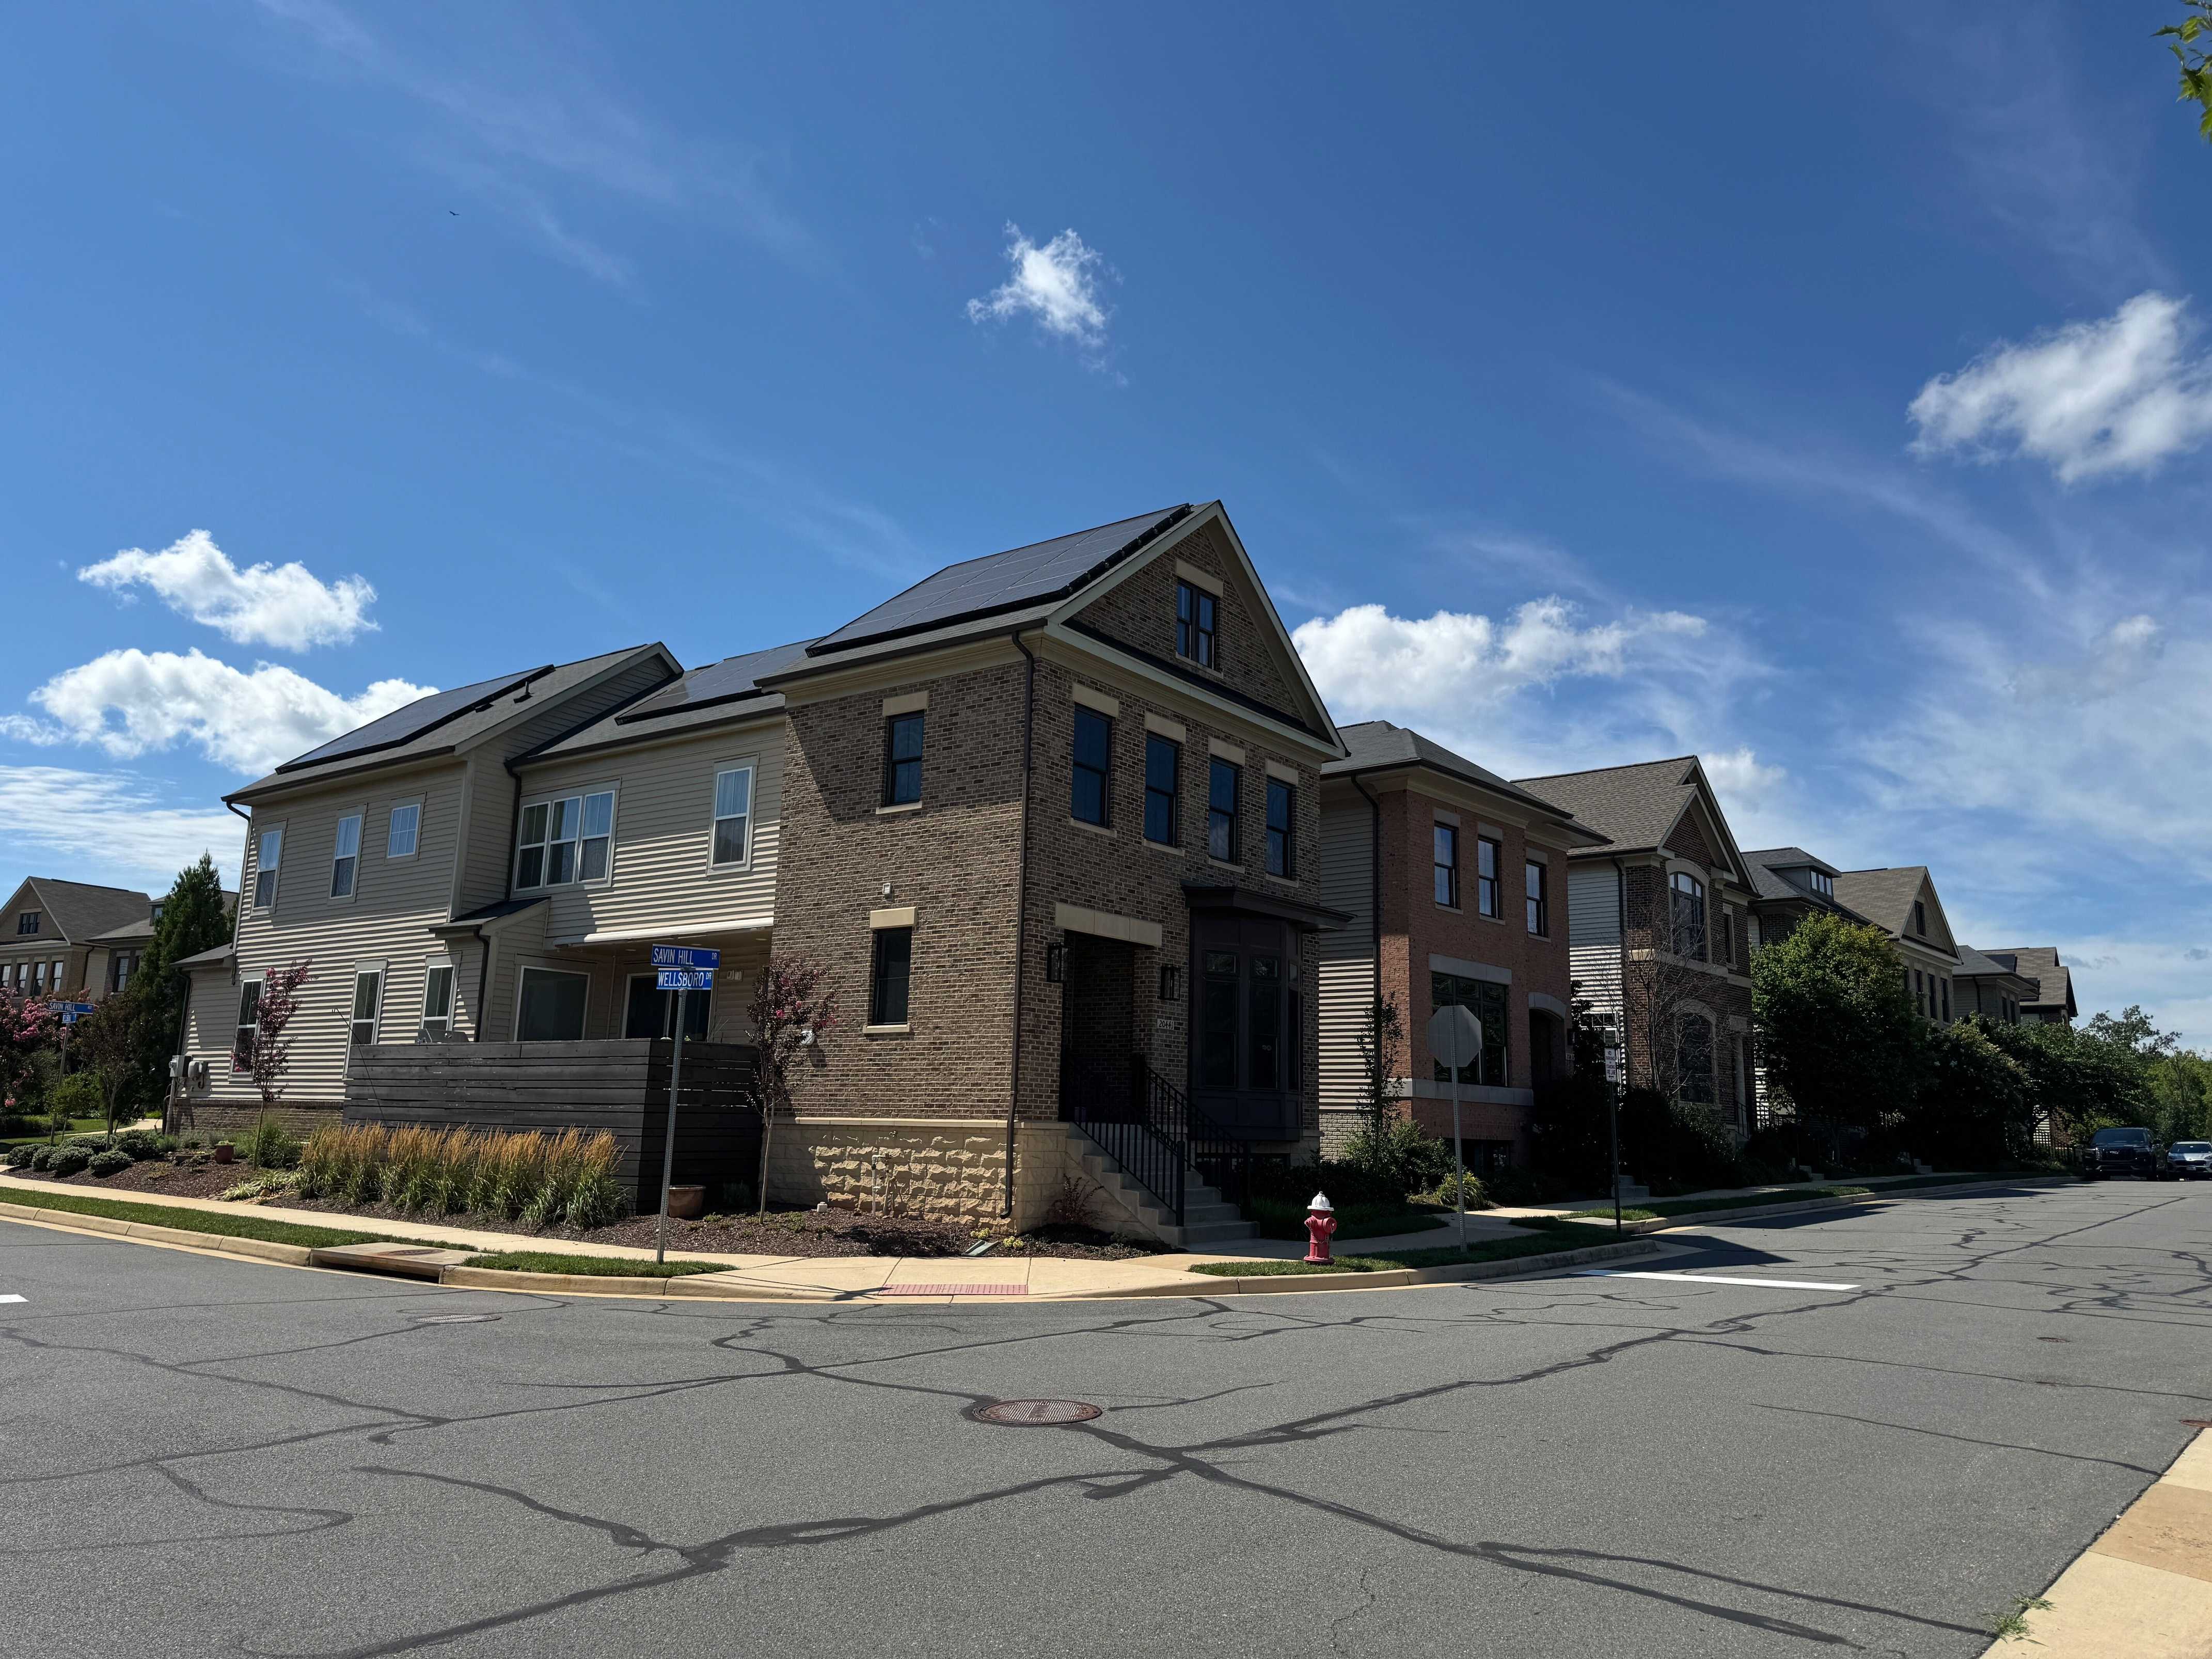
The highest offer is not automatically the best offer on your Northern Virginia home. Compare what you would keep after credits and selling costs, the buyer’s financing and contract conditions, and whether the closing and move-out dates work for you. A lower price can leave you with more money—or a more workable move—but it can also mean giving up value unnecessarily. Put the differences on paper before deciding.
In September 2026, Chris Colgan reported that his agents were hearing from sellers struggling with pricing expectations. His advice was to be realistic about the price. That observation is not a claim that every Northern Virginia neighborhood has the same market. It is a reason to evaluate an actual offer against comparable homes and your goals, rather than an ideal number.
Start with the dollars you would actually keep
Ask your agent and settlement company for an estimated seller net sheet for each serious offer. Use the same assumptions wherever possible. Start with the purchase price, then account for requested seller credits, agreed selling expenses, mortgage payoff, applicable taxes and prorations, and any other amounts you would owe. Keep a separate line for uncertain repairs or other unresolved costs.
A net sheet is a planning estimate, not the final settlement statement. Your payoff and prorations can change with the closing date. Negotiated compensation and services also need to reflect your actual agreements; there is no single fee percentage to assume for every sale.
A higher price can produce a lower starting net
Hypothetical example only: Imagine two offers on an Ashburn townhome. These are invented round numbers to show the math, not a client transaction, valuation or statement about current Ashburn prices.
| Offer | Price | Requested credit | Price minus credit |
|---|---|---|---|
| A | $750,000 | $20,000 | $730,000 |
| B | $740,000 | $5,000 | $735,000 |
Offer B is $10,000 lower on price but $5,000 higher after the stated credit. Neither final column is your take-home proceeds: payoff, selling expenses, taxes, prorations and any other obligations still come out. Different closing dates or contract terms could change the comparison again.
The CFPB’s Closing Disclosure explainer shows where seller credits appear in the buyer’s closing figures. The credit should match the agreement. Have the buyer’s lender confirm that the proposed credit works with the loan before you rely on it.
Then compare the conditions behind the number
Freddie Mac’s seller guidance recommends evaluating the price together with the closing date, fee provisions, contingencies and response deadline. You can accept, counter or reject an offer. Countering also carries the risk that the buyer moves on.
For each offer, have your agent explain the financing, appraisal, inspection and home-sale provisions actually written into that contract. Ask what must happen, by when, and what options each party has if it does not happen. A summary such as “strong financing” or “as is” is not a substitute for reading the terms.
Review documented financing or funds and the practical timeline. A larger deposit or cash offer can still have conditions; neither guarantees a closing. An offer with protections is not automatically a bad offer, either. The question is whether the price and terms make sense together.
Your move can change which offer fits
A Woodbridge seller buying in Gainesville might need sale proceeds before completing the next purchase. A Fairfax condo owner with a firm relocation date might care more about a dependable move-out plan. A Leesburg owner who has already moved could put less weight on occupancy flexibility. These are planning scenarios, not actual team transactions.
Price the consequences of each schedule: an extra move, storage, temporary housing, utilities or carrying two homes. Use real quotes and your own costs. Do not assign an arbitrary dollar value to “certainty” and call it a fact.
If you need time in the home after settlement, read our Northern Virginia seller rent-back guide. For the bigger move sequence, see selling before buying your next home.
When the higher offer is worth considering
The higher offer may be the better choice when its net proceeds are higher, the financing and conditions are supportable, and its dates suit your move. Do not discount an otherwise workable financed offer simply because a lower offer sounds easier.
A lower offer may fit better when the higher one requires enough credits or expenses to erase the difference, or when its timing conflicts with a costly obligation you cannot change. If you are not on a deadline and the price gap is substantial, giving up that money for convenience may be wrong for you.
Before responding, ask for a side-by-side comparison with five lines: estimated net proceeds, financing and funds, conditions and deadlines, closing and occupancy dates, and unresolved questions. Then decide what to accept or counter. Keep the decision grounded in the transaction terms.
Five frequently asked questions
Should I always accept the highest offer?
No. Compare the estimated net, contract conditions and move timeline. The highest offer may still be the best; the point is to verify why.
Is a seller credit the same as a lower price?
No. They change different parts of the transaction. Both affect your economics, but a credit must also work with the buyer’s financing and closing costs. Ask for the lender’s confirmation.
Is a cash offer guaranteed to close?
No. Review proof of funds, deadlines and every condition in the written offer. Cash removes the need for that buyer to obtain a mortgage only if the purchase is actually structured that way.
Can I counter the closing date instead of the price?
You can propose a change through your agent, subject to the contract and negotiation. The buyer can decline; do not assume a counteroffer will be accepted.
Who should prepare the final numbers?
Use your agent’s comparison for planning and have the settlement company confirm payoff, charges and settlement figures. Resolve contract interpretation questions with the appropriate real estate attorney.
Talk with the Chris Colgan Team about selling your Northern Virginia home. Bring your target move date and the offers you are considering so we can compare the numbers, conditions and next steps.
Sign up for my Northern Virginia breaking-news newsletter.
Prepared October 18, 2026. Sources: Freddie Mac and CFPB pages linked above; Chris’s September 19, 2026 direct pricing insight. Examples are illustrative, not local market statistics.
Chris Colgan
REALTOR® | Team Leader, Chris Colgan Team
Real Broker, LLC | Powered by PLACE
Call or text: 571-437-7575
Office: 571-621-7660
info@colganteam.com
8427 W Main St, Marshall, VA 20115
ColganTeam.com | ChrisColgan.com
Chris Colgan
Team Leader | Chris Colgan Team | REAL | PLACE
or another way