Categories
Buyer Guides, Northern Virginia Real EstatePublished September 28, 2026
Should You Buy a Northern Virginia Home If You Might Move in Two Years?
If you expect to leave Northern Virginia in one or two years, renting deserves serious consideration before you buy. A short ownership period gives you less time to absorb buying and selling costs, and you may need to sell before the market or your finances cooperate. Buying can still fit some situations, but the numbers should work without assuming rising prices or a future refinance.
I’m hearing from buyers who want to wait because of interest rates. One of my first questions is how long they actually expect to live in the home. A seven-to-ten-year plan is a different conversation from a one-to-two-year stay. That is the practical distinction I raised in September 2026—not a promise that a particular holding period guarantees a profit.
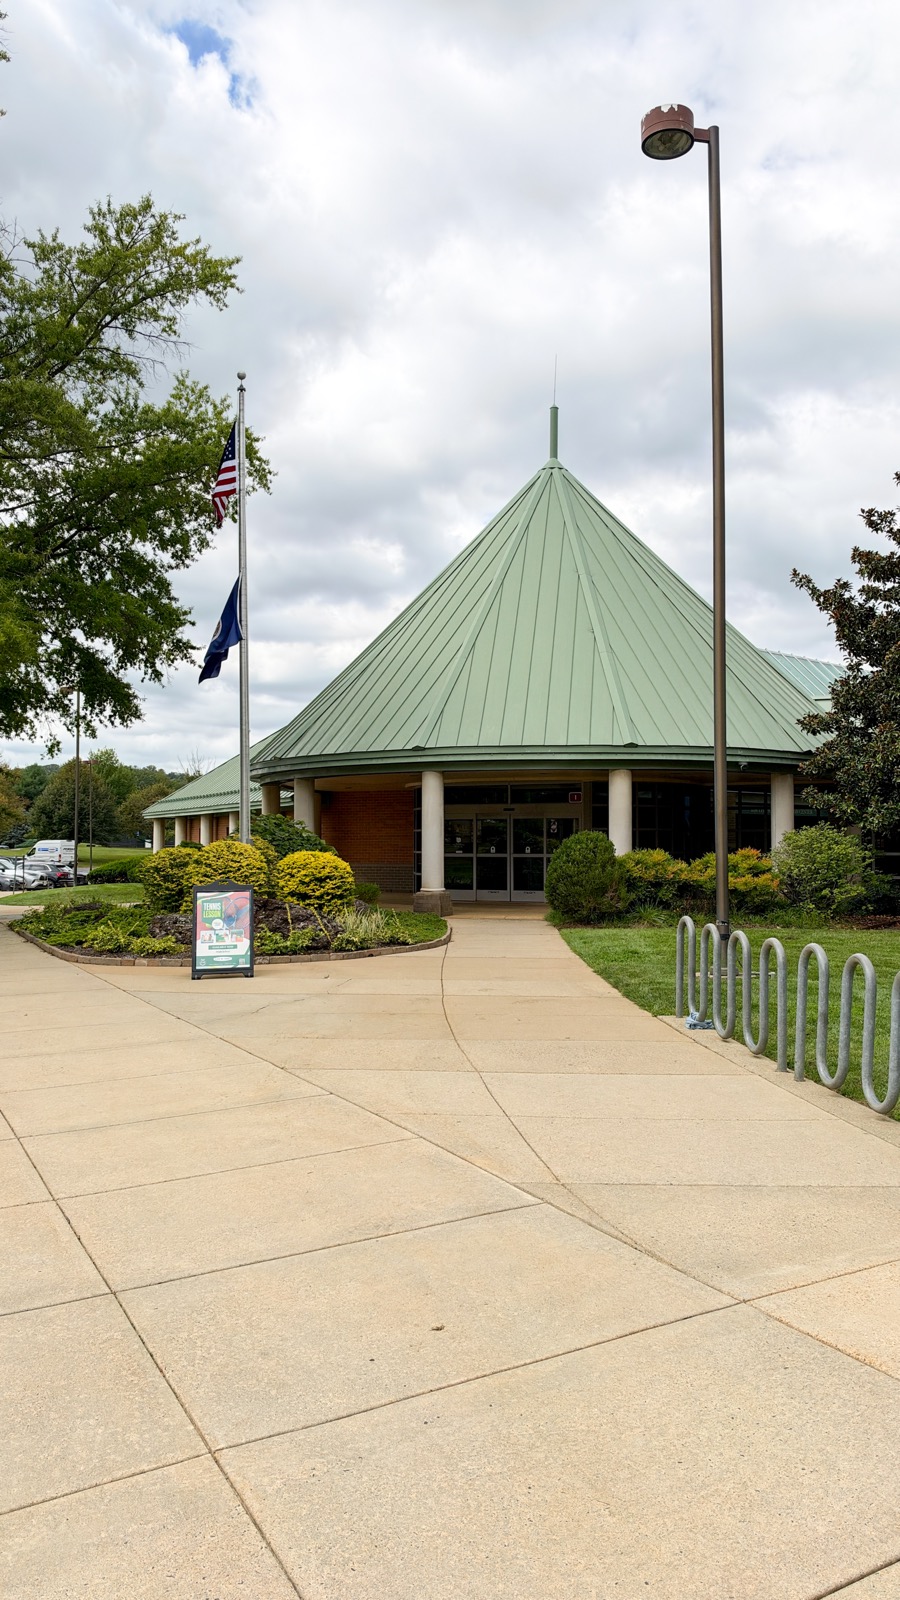
Photo: Ida Lee Park in Leesburg, from our local photo library. Use neighborhood visits to test your everyday routine before making a longer commitment.
Stay in the know across Northern Virginia.
Get local news, new openings and community updates from Chris Colgan’s Real NoVA newsletter.
Start with your likely move date
Put two dates on paper: when you expect to move and the earliest you might need to move. If a two-year work assignment could end after twelve months, evaluate both. A plan that works only if you stay much longer is not really a two-year plan.
The Consumer Financial Protection Bureau cautions that buying can be risky and expensive when you might move again within a few years. It recommends testing different assumptions when comparing renting and buying. There is no single break-even year that works for every property or household.
Renting also has limits: you are subject to the lease, renewal terms and the owner’s rules. You may have less control over improvements or whether you can stay after the lease ends. Compare those tradeoffs with the responsibility and flexibility you would actually have as an owner.
The purchase price is only the beginning
Get a written estimate for the cash needed to buy, the ongoing cost to own and the likely cost to sell. Keep the down payment separate from fees: it contributes to your equity, but that money is tied up and is not automatically returned in full when you sell.
The CFPB gives a general buyer closing-cost range of 2%–5% of the purchase price, excluding the down payment. On a hypothetical $600,000 purchase, that is $12,000–$30,000. This is an illustration using a national planning range—not a Northern Virginia quote, a local median price or a complete rent-versus-buy calculation.
For your actual comparison, ask the lender and settlement provider to explain each estimate. Add property taxes, insurance, association charges, maintenance, utilities and any mortgage insurance to the budget. Some amounts may already be included in the lender’s payment estimate; do not count them twice.
Then request a seller net estimate for a possible resale. Use the compensation and fees that would apply to your agreement, along with estimated payoff, preparation, moving costs and any buyer concession. Do not assume a standard commission or a fixed future selling cost.
Compare what you would have left after two years
Do more than compare the rent check with the mortgage payment. Ask your lender for the projected loan balance after 24 payments, then compare two complete scenarios:
- Rent: rent and expected increases, renter’s insurance, moving costs and applicable lease charges. Treat a refundable deposit separately. Account for the cash you would retain instead of using it to buy.
- Own: cash paid at purchase, monthly ownership costs, repairs and the cash you would receive—or need to bring—when selling after paying the loan and sale costs.
Principal paid down reduces the mortgage balance; it is not the same as interest or a fee. A comparison that treats every mortgage dollar as lost, or assumes every dollar becomes recoverable equity, misses that distinction.
Try a flat resale price and a lower resale price as well as an optimistic case. These are stress tests, not forecasts. The CFPB notes that transaction costs and declining prices can make moving after a few years difficult. Ask whether you could handle the result if a sale takes longer than expected.
What this looks like around Northern Virginia
Consider a buyer deciding between renting near work in Arlington and buying farther away in Woodbridge. Compare actual commute time, tolls, parking and workdays alongside housing costs. More space is useful only if the daily routine also works. Our I-95 proposal guide explains why an unbuilt transportation improvement should not be the basis of today’s home decision.
For someone moving to Leesburg or Ashburn without knowing the area well, a rental can provide time to test errands, work travel and the neighborhood before committing. Visit the places you expect to use on ordinary weekdays, not just during a pleasant weekend outing. Our Leesburg guide is a starting point for that research.
For a Fairfax condo, the monthly association charge and any known assessment belong in the comparison. Read the documents rather than assuming a lower purchase price means a lower total cost. See our condo questions to resolve before closing. These are decision scenarios, not claims about specific clients or current available rentals.
Refinancing is an option to evaluate, not the plan
A future refinance does not erase the cost of buying and selling. It also requires a new loan decision and can involve additional costs. The CFPB’s refinancing worksheet explains why the cost of the new loan matters alongside the payment.
Be comfortable with the loan you can obtain today. Future rates, your qualification and the value of the property may change. If the payment is workable only after an assumed rate drop, revisit the price range or rental option.
When buying might still make sense
Buying may remain worth evaluating if your move date is flexible, you can afford the current payment comfortably and you have enough reserves to absorb a repair or delayed sale. A verified employer relocation benefit could change the calculation, but use the actual policy and eligible amounts.
Do not treat “I’ll rent it out” as an automatic escape route. Before relying on that option, investigate association restrictions, loan and insurance requirements, achievable rent, management costs, maintenance and vacancy. You would be choosing a landlord business as well as a home.
Renting is often the more comfortable starting point when your departure date is firm, you are learning the area, or buying would leave little cash available. Ownership may offer stability and control, but you should not need a best-case resale to make the decision feel safe.
Frequently asked questions
Is two years always too short to own a home?
No. It is a reason to calculate carefully, not a universal rule. Your actual transaction costs, financing, rent alternative and ability to delay a sale matter.
Is renting just throwing money away?
Rent pays for housing and the flexibility provided by the lease. Ownership also has costs that do not build equity. Compare both complete options.
How much will I get back when I sell?
Start with the eventual sale proceeds, then subtract the mortgage payoff and selling expenses. That result is uncertain today; your down payment is not a guaranteed refund.
Should I buy now because I can refinance later?
Only buy if today’s payment and overall budget work. Treat a possible refinance as a separate future decision, including qualification and costs.
What should I send the team for a comparison?
Share your expected stay, earliest possible move date, work location, comfortable monthly budget and the rental and purchase options you are considering. Your lender can provide loan estimates and projected balances.
Let’s compare your actual options
Talk with the Chris Colgan Team about your Northern Virginia home search. Tell us whether this is a short assignment, an uncertain move or a place you hope to stay for years. We can help compare locations and organize the questions for your lender. If selling a current home is part of the plan, start with a selling consultation and net estimate.
Want more Northern Virginia news and local updates?
Join Chris Colgan’s Real NoVA newsletter and get the next edition in your inbox.
About Chris Colgan
Chris Colgan
REALTOR® | Team Leader, Chris Colgan Team
Real Broker, LLC | Powered by PLACE
Call or text: 571-437-7575
Office: 571-621-7660
info@colganteam.com
8427 W Main St, Marshall, VA 20115
ColganTeam.com | ChrisColgan.com
Source guidance checked September 28, 2026. Examples are illustrative, not loan quotes, current inventory or forecasts.
Chris Colgan
Team Leader | Chris Colgan Team | REAL | PLACE
or another way